EX-99.1
Published on October 21, 2026
Exhibit 99.1
October 21, 2026
Fellow Shareholders,
For the third quarter, we recorded net income to common stockholders of $12.6 million, or $0.52 per diluted share. Earnings for the quarter were affected by certain non-recurring items detailed at the end of this letter, which in aggregate reduced EPS by $0.02 for the quarter.
CEO Summary
As has become my custom, I will begin the letter with some thoughts about what is going well and what is not going as well regarding matters I believe to be of relevance to long-term investors.
For the first time in several years, the external freight environment and the internal maturity of our platform are moving in our favor at the same time. We spent the freight recession building network density, products, data assets, and infrastructure. The task now is increasingly straightforward: convert what we have built into revenue growth, operating leverage, and earnings.
We told investors we would invest through the freight cycle, and we did exactly that. Not everyone agreed with the strategy, but we were true to our word. Investors should expect that same level of commitment as we now take the steps necessary to translate that potential into earnings performance consistent with our historical results and beyond. Doing so will demonstrate the returns on the investments we have made. Our priorities have evolved, but our commitment to delivering on what we say has not.
The Metrics That Matter Most
| North Star Metrics | Long-Term Target | 3Q26* | 2Q26* | △ From Prior Quarter | |||||||||||||||||||
| Transportation Revenue Growth | > 15% | 37.8 | % | 30.9 | % | 6.9 | % | ||||||||||||||||
| Factoring Operating Margin | > 40% | 43.0 | % | 39.4 | % | 3.6 | % | ||||||||||||||||
| Payments EBITDA Margin (ex-LoadPay) | > 50% | 39.0 | % | 34.0 | % | 5.0 | % | ||||||||||||||||
| Intelligence Gross Margin | > 85% | 84.4 | % | 84.7 | % | (0.3 | %) | ||||||||||||||||
* Growth figures are YoY, all other metrics are for the quarter indicated.
The North Star metrics – and the metrics underneath them – speak for themselves this quarter. Transportation revenue is up 37.8% over last year and roughly 1/3 of that growth is organic versus purely market tailwinds. Factoring operating margin is above the long-term target, and we have added 706 net new customers this year. Payments EBITDA margin (excluding LoadPay) is just under 40% and trending higher. LoadPay revenue grew 21.3% sequentially for the quarter. The point is that there is a lot to like and still, there are areas to improve.
Many of the forces reshaping trucking are difficult for the industry and yet constructive for Triumph. We recognize the real challenges many market participants face and do not minimize them. At the same time, those challenges do not change our view that, but for diesel costs, the freight market is healthier than it has been in a long time. For years, we have been building a value chain and platform particularly well suited to this environment. As a result, we have considerable momentum, and we increasingly believe it is durable.
One Out, One In – Planned Changes to 2027 North Star Metrics
For the year 2027, we will be removing one North Star Metric and adding another.
Intelligence gross margin does not tell investors or management what we really care about – how are we doing at growing revenue (and eventually profitability) in that segment? Top-line growth has been sluggish as we have churned the customer base. We have more to say about this below. In any event, given the structure of our Intelligence segment, our gross margin should not move much and is not as important as revenue growth. As a result, we are dropping the Intelligence gross margin as a North Star metric, although we will continue to report on it every quarter.
Beginning in 1Q, we will be adding a North Star metric tied to total non-interest expenses. That metric will be < $400mm for the year 2027. Achieving that target while allowing for inflation and investing for growth in our transportation business
1
means we will need to realize at least $20 million of efficiencies from our current run rate. For the long term, a ceiling on total non-interest expenses is a worthy North Star metric because it goes beyond the operating margins for our transportation segments and measures efficiency of the entire enterprise.
More Thoughts on Expenses for 3Q
While we are on the topic of expenses and becoming leaner for the long term, our full quarter expenses came in at $102 million. We did not accrue the additional bonus we called out as possible last quarter even though we outperformed on several important metrics. As I said above, we are in the process of pursuing efficiencies across the enterprise. Our objective is not simply to spend less; it is to produce more with the investments we have already made. Every dollar of expense must go further than it did before, and we adjust compensation accordingly.
During the quarter, we booked expenses primarily related to technology and occupancy that we do not expect to recur in future quarters. Even though unusual, to be transparent, we do not consider them to be non-core. The impact of that additional expense during the quarter was $1.1 million.
From Investing to Operating Leverage
For several years, our story required investors to look ahead. We were building network density, products, data assets, and infrastructure that carried real expenses before generating their full economic return. That is changing. Investors should increasingly be able to judge the success of those investments through revenue growth, margin expansion, and earnings.
The math for 2027 is straightforward – if we deliver on our North Star expense metric, record normalized credit costs and grow Transportation revenue by low double digits over 2026, the EPS output is roughly $3.50. I offer the math not as a precise forecast, but to illustrate operating leverage within the model. Whatever the final growth number is for 2027, there is still a very large market opportunity for us in transportation to go win for the foreseeable future.
Fewer Carriers Does Not Mean Fewer Triumph Customers
Of the many things I am proud of this quarter, I want to point out client growth in our Factoring and LoadPay lines of business. Outside observers have espoused many theories on what the re-regulation of trucking and higher diesel prices might do to our customer base. I won’t argue with those general observations. Indeed, regulatory enforcement has taken many drivers off the road, and litigation and fraud risk has slowed the rate of new carrier formation compared to prior cycles.
That general observation, however, does not tell Triumph’s part of the story. The number of carriers in the market defines the size of our opportunity, but it does not determine our share of it. Our growth this quarter demonstrates the reach of our platform and our ability to continue adding customers even as the industry is flat or contracting. We are not immune to market conditions, but the value chain we have built and the reputation we have earned over 15 years have put us in the position to continue gaining share.
Some investors may recall that we slowed our growth in factoring for a few years. There were strategic reasons for that decision principally around our efforts to build an open-loop payments network. With hindsight, I believe we were too cautious in that approach. Moreover, our understanding of the strategic value of Factoring has evolved. We once viewed it primarily as an attractive financial business. Today, we increasingly view it as the principal carrier-acquisition gateway into the Triumph value chain. A factoring customer can become a LoadPay customer, an Intelligence customer and a user of other Triumph services. Seen through that lens, growing Factoring strengthens rather than competes with the Network.
When a theoretically sound strategy does not develop as expected, you should own it and change course. That is what we have done, and I expect that more growth is in store for Factoring – both for our first-party business and for our FaaS partners. Given our value chain, there is much more to factoring than just financing receivables, and we intend to take full advantage of it.
What is $100 Worth?
Given the foregoing, Triumph’s earnings will continue to have a strong correlation to the average invoice sizes we purchase from our Factoring clients. For 3Q, the average transportation invoice size in our Factoring business was $2,210. For the first 16 days of 4Q, average transportation invoice sizes have increased to $2,288.
The four main inputs for trucking – wages, fuel, equipment costs, and insurance – are all continuing to trend upward. Fuel is up materially since the beginning of the Iran conflict. Investors sometimes ask how sensitive our average invoice price is to the cost of diesel. That question cannot be answered with precision because there are many forces at play setting the
2
market rate. For some of our larger fleet customers with shipper-direct contracts, the fuel surcharge per mile is running nearly $1.00, which is extraordinarily high by historical standards; however, that surcharge is only relative to the pricing scale when contract rates were set. For the average load, we estimate that fuel is roughly 20-25% of the cost, being second only to driver wages.
For example, dry van revenue per mile is up ~40% YoY, but diesel costs are up 67% if you use the price at the pump, which is not what most truckers pay due to negotiated fuel discounts. Beyond that cost pressure, it is hard to find qualified drivers, which is pushing wages to $0.70 a mile and beyond in many markets. Insurance costs continue to increase, in part due to nuclear verdicts. The cost to purchase equipment has gone up, and the cost to finance it has also gone up as interest rates have risen.
In sum, we cannot give a precise calculation for what diesel prices will do to the average invoice because it depends on too many factors, not the least of which is demand. What we can say is that all of the four major inputs listed above are currently inflationary. As a result, the revenue per mile a trucker must generate (and thus, the average invoice size) is almost certainly going to be double-digit percentages above historical norms unless and until market forces change. Personally, I am not convinced that current rates have reached a level where the average law-abiding trucking company can earn its true cost of capital. Averages do not tell the full story – carriers with longstanding customer relationships or highly efficient operations are doing considerably better in this market than they have in several years.
Whatever the market does, here is a helpful calculation for investors: for every $100 move higher in the average invoice price, Triumph should generate roughly $12 million in incremental annual revenue, $8.5 million in pretax earnings and $0.27 EPS annualized. The inverse is also true when invoice sizes decline.
Thoughts on Credit
Credit expense increased this quarter, primarily reflecting specific commercial real estate exposures in our Banking segment, and provisioning associated with growth in our transportation businesses. We are not satisfied with the volatility these CRE exposures have introduced into an otherwise improving operating picture. Our work to reduce non-core credit exposures continues, and we remain focused on making Banking a more predictable contributor to consolidated earnings. Transportation credit performance remains favorable on a risk-adjusted basis as it has for the last 15 years.
Growing Intelligence Revenue
Revenue growth in our Intelligence segment has also not met our expectations. Difficult market conditions for smaller brokers contributed to that result, but that was not the only factor. Some of the products we introduced did not become sufficiently embedded in customer workflows to produce durable renewals, and we did not consistently translate our differentiated data into clear, repeatable customer value. We own those shortcomings and we have learned from them.
At the same time, the underlying customer demand gives us reason for confidence in the future. Since the end of 2025, we have added 63 broker clients while 53 have gone out of business or canceled their subscription, resulting in a net increase of ten. Our newer customers generally have stronger market positions than the legacy customers they are replacing. This reinforces our belief in the original thesis for creating the Intelligence segment.
Our experience has also clarified where Triumph’s advantage is greatest: the transaction-backed data created through our position in freight settlement. We do not need to build every application or customized model that can be developed from that data. Those are valuable, but there is also real value in the data itself. We will continue to develop our own products, while also enabling customers and partners to build analytics, benchmarks and decision tools upon our data assets. This approach expands the go-to-market opportunity and reflects a broader reality: large and sophisticated market participants are always searching for better data and only sometimes searching for better models.
To put a finer point on what differentiates our data, here is a way to filter various data sources: Postings are advertisements. Quotes are opinions. Tenders are expectations. Payments are facts. Because we sit at the point where freight is settled financially, we have unparalleled visibility into what actually moved, at what price, and who ultimately got paid. That provides a uniquely grounded view of market conditions at precisely the time when understanding the identity, quality and economics of capacity matters more than ever.
Frequently Asked Question – What does Autonomous Trucking Mean for Triumph?
Since I am asked about autonomous trucking in most investor meetings, I will offer a few thoughts here. Autonomous technology is coming. I have sat in many of our customers’ newer trucks and seen firsthand the advanced safety features already built around this technology. Fully autonomous trucks are the next step. It will take years to commercialize on a nationwide scale, but I believe it will happen in certain segments of trucking.
3
What I am less convinced of is that autonomy presents an existential threat to our Factoring business. It may be disruptive to some small owner-operators, particularly if autonomous trucking favors larger fleets with access to capital, dense lanes, and the infrastructure necessary to operate and maintain the equipment. But trucks do not stop being businesses simply because there is no driver in the cab. Carriers will still require capital, payments, settlement, and financial infrastructure. Companies with autonomous fleets will still require warehousing/docking facilities and maintenance operations. Our larger customers, which generate the majority of our Factoring revenue, are well positioned to adapt their fleets as the technology evolves, and we intend to help them do so.
A Different Freight Cycle: Defensibility and Durability
This freight environment is more favorable for Triumph than the market appreciates.
Capacity exits, regulatory enforcement, driver shortages, and elevated operating costs continue to tighten truckload supply, supporting higher rates despite only moderate freight demand growth. Across the industry, carriers are reporting stronger bid activity, improving pricing, positive levels of tender rejections, and increasing customer urgency around securing committed capacity. Spot and contract rates remain well above prior-year levels, and most management teams in our space view recent softness as seasonal rather than cyclical deterioration.
What makes this cycle unusual is that pricing is strengthening before demand. Recent shipper surveys show freight-volume expectations roughly flat, even as expectations for capacity tightness and pricing continue to rise. What we see in our own transaction data is that the constraint is on the supply side.
The scarce resource in freight today is not trucks. It is trusted, deployable capacity, because a truck that cannot be verified and deployed with confidence is not defensible, and thus, is not truly usable capacity.
Freight is moving from a market defined by abundant capacity to one defined by defensible capacity. The key question is no longer whether a truck is available, but whether that capacity can be trusted, verified, insured, financially capable, and thus deployed with confidence. While there may still be plenty of trucks on the road, the pool of carriers that brokers and shippers are willing and able to use is shrinking. As a result, the economics of freight are changing and suggest the market is placing a growing premium on commercially usable capacity.
In a market where capacity increasingly must be verified before it can be trusted, identity, transaction history, payment history and financial behavior become more valuable. Those are increasingly connected to the financial transaction that sits at the center of the Triumph Network.
Payments
1.Analysis of Financial and Operational Performance for the Quarter
2.LoadPay Update & Where Do Truckers Bank?
Analysis of Financial and Operational Performance for the Quarter. The Payments business has graduated from logo acquisition to revenue growth to EBITDA margin expansion and, finally, is becoming a driver of earnings. As a result, we will provide more commentary on operating income in future letters alongside insights on revenue growth and EBITDA margin. Operating income grew 46.4% QoQ to $4.2 million. Over the next several quarters, we expect operating income to continue to grow through a balanced combination of organic revenue growth and cost savings with less contribution from repricing.
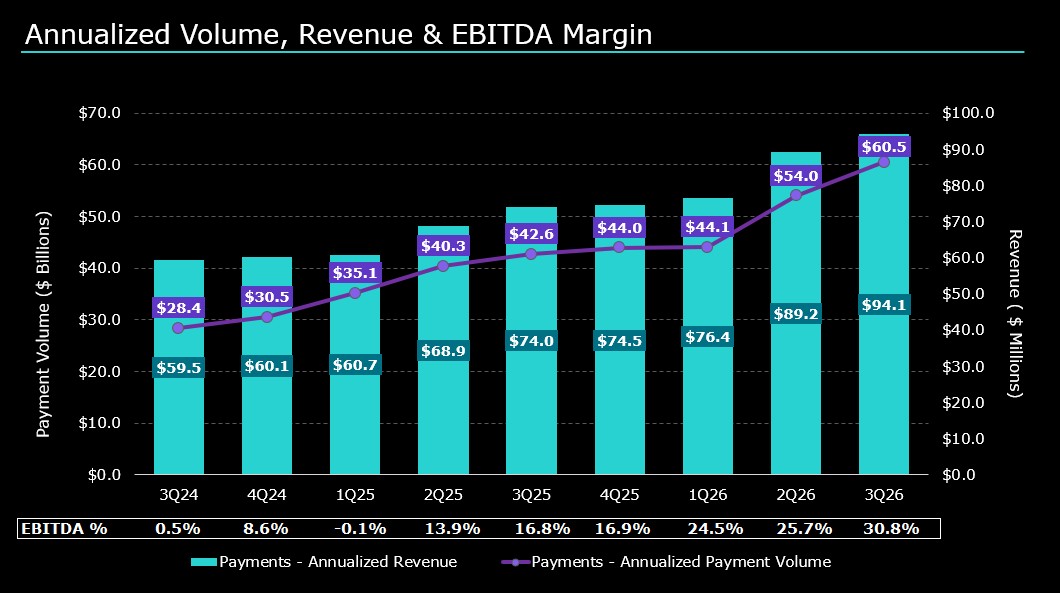
Revenue was $23.5 million, an increase of 5.6% QoQ and 27.2% YoY. Revenue growth reflected a combination of contractual repricing, invoice growth and new relationships. Payment processing increased 4.2% QoQ to 9.5 million invoices, representing $15.1 billion of payment volume. Broker revenue per invoice increased to $1.43, and our product attachment ratio grew slightly to 1.33. The important point is not any one metric in isolation; it is that we are monetizing a network that is already scaled while continuing to improve the value delivered to customers.
Payments remains largely a per-invoice business, so invoice counts and revenue per invoice are generally more useful indicators of operating progress than payment dollars alone. Higher invoice values expand the amount of money flowing through the network and reinforce its strategic importance, but our direct revenue levers remain customer wins, product attachment, and fair value-based pricing. We expect those levers to continue contributing to revenue growth and margin expansion.
We also reduced expenses in this segment during the quarter, which contributed to improvement in EBITDA margin to 30.8% in total, or 39.0% excluding LoadPay. We anticipate continued reductions in Payments expenses as process improvements from our lean initiatives and deployment of AI will more than offset incremental investments in LoadPay.
4
Importantly, these process improvements are also improving our customer experience by streamlining document processing and eliminating exceptions and escalations back to our broker customers.
| September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | Current Quarter Q/Q | Current Year Y/Y | |||||||||||||||||||||||||||||||||||||||||||||||
| For the Qtr Ending | Change | % Change | Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||
| Payments: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Invoice Volume | 9,467,000 | 9,086,400 | 8,220,371 | 9,053,274 | 8,826,848 | 380,600 | 4.2 | % | 640,152 | 7.3 | % | ||||||||||||||||||||||||||||||||||||||||||
| Payment Volume | $ | 15,132,596,000 | $ | 13,492,237,000 | $ | 11,014,040,000 | $ | 10,995,478,000 | $ | 10,662,418,000 | $ | 1,640,359,000 | 12.2 | % | $ | 4,470,178,000 | 41.9 | % | |||||||||||||||||||||||||||||||||||
Network Engagement[1] | 65.3 | % | 65.6 | % | 66.1 | % | 64.2 | % | 63.4 | % | (0.3) | % | (0.5) | % | 1.9 | % | 3.0 | % | |||||||||||||||||||||||||||||||||||
| Average Float | $ | 570,352,000 | $ | 567,839,000 | $ | 534,674,000 | $ | 518,182,000 | $ | 484,582,000 | $ | 2,513,000 | 0.4 | % | $ | 85,770,000 | 17.7 | % | |||||||||||||||||||||||||||||||||||
| Fee Revenue | $ | 12,029,000 | $ | 11,159,000 | $ | 9,450,000 | $ | 8,913,000 | $ | 8,791,000 | $ | 870,000 | 7.8 | % | $ | 3,238,000 | 36.8 | % | |||||||||||||||||||||||||||||||||||
| Total Revenue | $ | 23,535,000 | $ | 22,296,000 | $ | 19,104,000 | $ | 18,628,000 | $ | 18,503,000 | $ | 1,239,000 | 5.6 | % | $ | 5,032,000 | 27.2 | % | |||||||||||||||||||||||||||||||||||
| EBITDA margin | 30.8 | % | 25.7 | % | 24.5 | % | 16.9 | % | 16.8 | % | 5.1 | % | 19.8 | % | 14.0 | % | 83.3 | % | |||||||||||||||||||||||||||||||||||
| EBITDA Margin (ex-LoadPay) | 39.0 | % | 34.0 | % | 34.0 | % | 29.5 | % | 28.2 | % | 5.0 | % | 14.7 | % | 10.8 | % | 38.3 | % | |||||||||||||||||||||||||||||||||||
| LoadPay: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| # of Accounts | 12,217 | 10,204 | 8,065 | 5,892 | 4,421 | 2,013 | 19.7 | % | 7,796 | 176.3 | % | ||||||||||||||||||||||||||||||||||||||||||
| # of Active Carrier Accounts | 4,788 | 4,004 | 3,157 | 2,487 | 1,916 | 784 | 19.6 | % | 2,872 | 149.9 | % | ||||||||||||||||||||||||||||||||||||||||||
| Revenue per Account (Ann.) | $ | 265.29 | $ | 281.05 | $ | 252.21 | $ | 248.33 | $ | 234.70 | $(15.76) | (5.6) | % | $30.59 | 13.0 | % | |||||||||||||||||||||||||||||||||||||
| Revenue per Active Carrier Account (Ann.) | $ | 668.98 | $ | 706.89 | $ | 633.10 | $ | 572.15 | $ | 516.78 | $(37.91) | (5.4) | % | $152.20 | 29.5 | % | |||||||||||||||||||||||||||||||||||||
| LoadPay Funding | $ | 223,017,000 | $ | 195,063,000 | $ | 118,384,000 | $ | 84,770,000 | $ | 53,042,000 | $ | 27,954,000 | 14.3 | % | $ | 169,975,000 | 320.5 | % | |||||||||||||||||||||||||||||||||||
| Average Interchange Fees | 1.54 | % | 1.58 | % | 1.62 | % | 1.68 | % | 1.64 | % | (0.04) | % | (2.5) | % | (0.10) | % | (6.1) | % | |||||||||||||||||||||||||||||||||||
| Cross Segment: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Broker Revenue Per Invoice* | $ | 1.43 | $ | 1.39 | $ | 1.31 | $ | 1.16 | $ | 1.15 | $0.04 | 2.9 | % | $0.28 | 24.3 | % | |||||||||||||||||||||||||||||||||||||
| PAR** | 1.33 | 1.32 | 1.30 | 1.33 | 1.31 | 0.01 | 0.8 | % | 0.02 | 1.5 | % | ||||||||||||||||||||||||||||||||||||||||||
*Broker Revenue per Invoice is calculated using unique broker invoice volume, referring to Invoices from our broker Payments and Audit services as well as our Intelligence services to brokers, and broker revenue, referring to revenue generated by our broker Payments and Audit services (Broker Fee Income + Quickpay Interest Income) + broker Intelligence revenue.
**PAR indicates product attachment rate and measures cross-selling of Payments, Audit, and Intelligence across our broker clients.
In the chart below, we graphically highlight the continued revenue growth and its trend over the last eight quarters against the backdrop of our Payment volumes. We have generated a ~26% CAGR in revenue over the last two years.
5
LoadPay Update. LoadPay ended the quarter with 12,217 total accounts and 4,788 active carrier accounts. Revenue for the quarter was $0.8 million, up 262.8% YoY and 21.3% QoQ. Annualized revenue per account was $265 and annualized revenue per active carrier account was $669, a 13.0% and 29.5% improvement over 3Q25, respectively. Funding through LoadPay totaled $223 million. These measures allow investors to distinguish account acquisition from actual utilization, which is the proof point that matters most at this stage.
Our focus has expanded from opening new accounts to becoming the primary financial operating account for carriers. That requires more of a trucker's workflow to live inside LoadPay, including receiving payments, retaining balances, managing factoring activity, paying expenses, and eventually consuming additional Triumph services. We expect continued product development and distribution through Factoring, FaaS, and broker relationships to increase account openings and utilization.
We have received questions from investors about our main competition for LoadPay. The simplest answer is other banks and credit unions, with a substantial weighting towards banks. Combined, there are roughly 9,000 of them in the United States. Over the last year, our Payments, Factoring and LoadPay products have sent funds to 2,499 unique financial institutions. The actual number of institutions where truckers bank is almost certainly higher than that figure because many of our payments go first to other factoring companies, obscuring where the funds ultimately reside.
What is the takeaway? Truckers bank everywhere. They use money center banks, super-regionals, community banks, and credit unions. What we know for sure is that none of these institutions wake up every day thinking about trucking the way Triumph does – and without an industry focus, why would they? But specialization alone is not enough. It is one thing to build a compelling product; it is another to have the distribution to put that product in front of customers.
This is where Triumph’s value chain becomes important, because in a value chain one activity reinforces another. This year, we expect to disburse approximately $79 billion in payments to carriers, including roughly $61 billion through Payments and $18 billion through Factoring. At our current run rate, approximately $1 billion, or only 1.1%, is being funded into LoadPay accounts. Our opportunity is to capture more of the money already flowing through Triumph. We intend to do that by meeting carriers across the breadth of their financial needs, including factoring, banking, equipment finance, insurance, and business intelligence. By combining those capabilities with our existing distribution, we can build a differentiated financial platform designed specifically for carriers, something traditional banks and credit unions are not positioned to replicate.
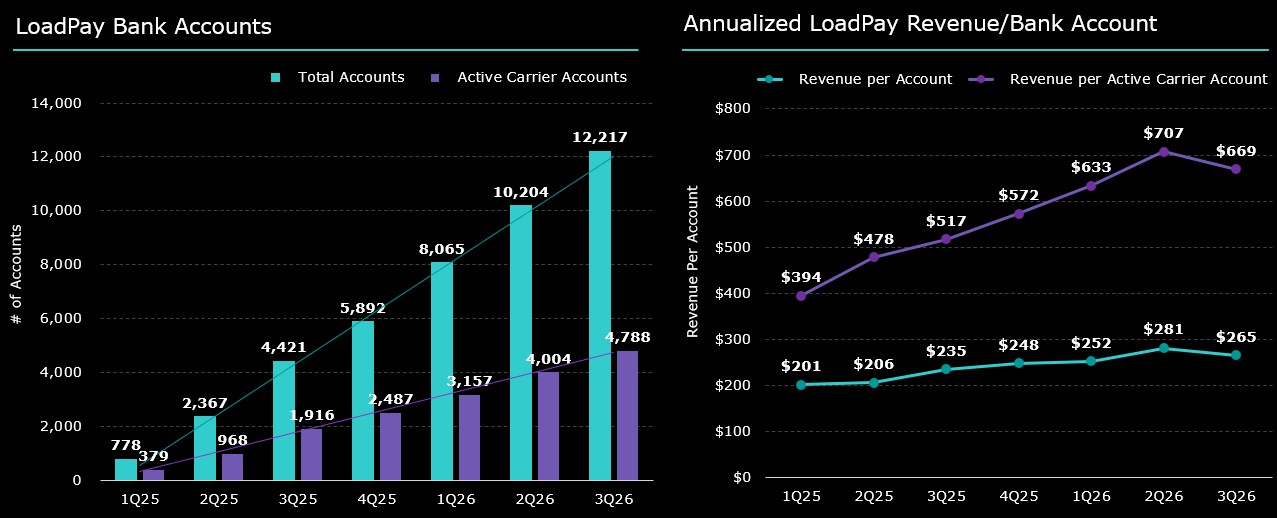
A few words of explanation on the chart above. For the quarter, total revenue increased approximately 21%, while both total and active accounts grew approximately 20%. Revenue per account is calculated using the number of accounts on the last day of the quarter against revenue earned during the final month of the quarter. Because a significant portion of our account growth occurred late in the quarter, those new accounts are fully reflected in the denominator but contributed only a partial month of revenue. As a result, the decline in revenue per account is largely a function of timing rather than underlying economics. Put plainly, the graph understates what was a strong quarter for LoadPay.
6
Factoring
1.Analysis of Financial and Operational Performance for the Quarter
2.Growth, Automation, and Margin Durability
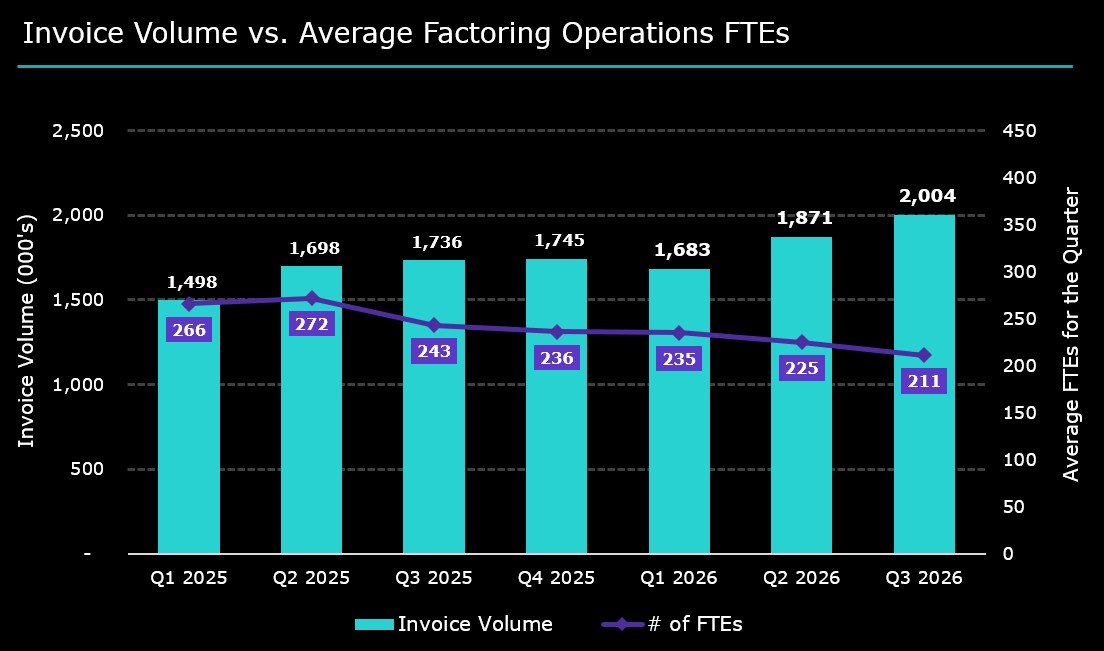
Analysis of Financial and Operational Performance for the Quarter. The Factoring segment delivered pretax operating income of $24.5 million. Revenue was $57.0 million, an increase of 7.5% QoQ and 43.6% YoY, and pretax operating margin was 43.0%. Total purchased volume reached $4.5 billion across 2.0 million invoices. The average transportation invoice was $2,210, while client count increased to 7,947. These results reflect a combination of client growth, market-share gains, higher invoice values, and continued improvement in processing productivity.
Factoring remains both an attractive financial business and the principal carrier-acquisition gateway into the Triumph value chain. When we win a factoring relationship, we have an opportunity to serve that carrier through LoadPay, equipment finance, insurance, fuel, and Intelligence. The economic value of Factoring therefore extends beyond the margin earned on an individual receivable. That broader relationship is one reason renewed growth in this business remains a strategic priority.
| September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | Current Quarter Q/Q | Current Year Y/Y | |||||||||||||||||||||||||||||||||||||||||||||||
| For the Qtr Ending | Change | % Change | Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||
| Factoring: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Invoice Volume | 2,004,137 | 1,870,938 | 1,683,160 | 1,744,811 | 1,735,860 | 133,199 | 7.1 | % | 268,277 | 15.5 | % | ||||||||||||||||||||||||||||||||||||||||||
| Purchased Volume | $ | 4,503,394,000 | $ | 4,117,210,000 | $ | 3,262,610,000 | $ | 3,119,443,000 | $ | 2,997,895,000 | $ | 386,184,000 | 9.4 | % | $ | 1,505,499,000 | 50.2 | % | |||||||||||||||||||||||||||||||||||
| Average Transportation Invoice Size | $ | 2,210 | $ | 2,160 | $ | 1,897 | $ | 1,751 | $ | 1,690 | $ | 50 | 2.3 | % | $ | 520 | 30.8 | % | |||||||||||||||||||||||||||||||||||
| Invoices / Client | 252 | 243 | 226 | 241 | 236 | 9 | 3.7 | % | 16 | 6.8 | % | ||||||||||||||||||||||||||||||||||||||||||
| Discount Rate | 1.26 | % | 1.29 | % | 1.28 | % | 1.28 | % | 1.29 | % | (0.03) | % | (2.3) | % | (0.03) | % | (2.3) | % | |||||||||||||||||||||||||||||||||||
| Avg Daily Purchases* | $ | 69,283,000 | $ | 65,353,000 | $ | 53,485,000 | $ | 50,314,000 | $ | 46,842,000 | 3,930,000 | 6.0 | % | 22,441,000 | 47.9 | % | |||||||||||||||||||||||||||||||||||||
| # of Customers | 7,947 | 7,705 | 7,436 | 7,241 | 7,355 | 242 | 3.1 | % | 592 | 8.0 | % | ||||||||||||||||||||||||||||||||||||||||||
| PAR | 1.20 | 1.20 | 1.19 | 1.17 | 1.16 | 0.00 | — | % | 0.04 | 3.4 | % | ||||||||||||||||||||||||||||||||||||||||||
| Operating Margin | 42.96 | % | 39.39 | % | 34.72 | % | 32.61 | % | 20.71 | % | 3.57 | % | 9.1 | % | 22.25 | % | 107.4 | % | |||||||||||||||||||||||||||||||||||
Growth, Automation, and Margin Durability. Our net client count has trended positive over the last nine months, and yet we have lots of opportunity in front of us. Our data indicates there are more than 90,000 factored carriers active in the U.S., and we serve approximately 8,000 of them currently. We are averaging 78 net new client additions per month, including a healthy mix of small and larger carriers. Year-to-date, we have added 706 net new clients. Most have been organic additions, but we are also seeing strong growth through FaaS as our partners combine freight opportunities with Triumph’s carrier solutions.
At the same time, we are becoming more efficient at serving our customers. Instant decisioning, cash application and collections automation, and workflow simplification are allowing us to process more business with fewer resources. From 3Q25 to 3Q26, we reduced our direct cost to service an invoice by 20.1%. Our objective is not simply to reduce headcount. It is to increase capacity, improve the customer experience, and allow revenue to grow faster than expenses.
These productivity gains matter because they make Factoring’s earnings less dependent on the freight cycle. A $100 move in average invoice price, up or down, changes annual pretax income by approximately $8.5 million with little corresponding change in expense. Higher invoice prices therefore provide meaningful operating leverage, as they are doing today. We believe there are compelling reasons invoice prices may remain higher for longer, but we do not intend to build a strategy that requires that. We intend to grow Factoring by growing market share, lowering unit costs, and increasing the value of each customer relationship through the broader Triumph platform – including strengthening our Network. Higher invoice prices are an accelerant to that strategy, not its foundation.
7
Intelligence & Freight Market Update
1.Analysis of Financial and Operational Performance for the Quarter
2.Freight Market Update: Defensible Capacity Is the Constraint
Analysis of Financial and Operational Performance for the Quarter. Intelligence generated revenue of $2.4 million, gross margin of 84%, and EBITDA margin of (50.3)%. We are still in the early days of Intelligence, but the mandate is clear – the segment must demonstrate that its differentiated transaction data can be converted into repeatable products, durable recurring revenue, and improving retention. High gross margin creates attractive potential, but the proof must come through commercial results.
As I said in the CEO summary, our strategy for Intelligence is also evolving from simply building applications to building a platform. Triumph possesses transaction-backed freight data that is difficult for others to replicate at scale. We will continue turning that data into our own products, but we can also enable customers and partners to use it as the foundation for their own analytics, benchmarks, and decision tools. The more ways our data can be used, whether through a Triumph product or something built on top of our platform, the larger the commercial opportunity becomes.
| September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | Current Quarter Q/Q | Current Year Y/Y | |||||||||||||||||||||||||||||||||||||||||||||||
| For the Qtr Ending | Change | % Change | Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||||||
| Intelligence: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Revenue* | $ | 2,360,000 | $ | 2,389,000 | $ | 2,397,000 | $ | 2,347,000 | $ | 2,338,000 | $ | (29,000) | (1.2) | % | $ | 22,000 | 0.9 | % | |||||||||||||||||||||||||||||||||||
| EBITDA Margin | (50.3) | % | (81.7) | % | (68.7) | % | (42.2) | % | (94.6) | % | 31.4 | % | (38.4) | % | 44.3 | % | (46.8) | % | |||||||||||||||||||||||||||||||||||
Freight Market Update: Defensible Capacity Is the Constraint. Our transaction data suggests the market is already operating with less flexibility than headline capacity metrics imply. We see typical seasonal volume patterns against a known constraint in capacity. Our data suggests that the industry has substantially less capacity available to absorb a recovery in demand than traditional headline measures would imply. Broker buy rates remain elevated across all major equipment types, rising roughly 48% YoY in September, even as freight demand remains relatively stable. Historically, that type of pricing inflation would have required a significant demand surge. Today, it is occurring before one arrives.
8
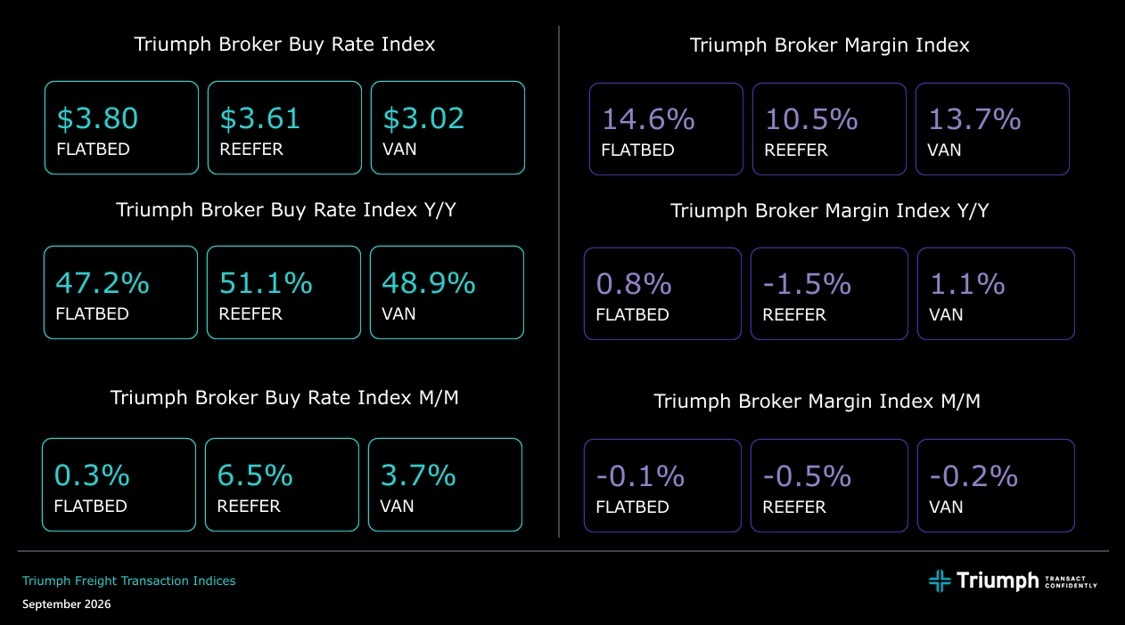
The implication is that freight capacity appears increasingly constrained on the supply side. Regulatory enforcement, carrier qualification standards, insurance requirements, fraud mitigation efforts, and driver compliance and training requirements are all raising the threshold for what capacity can participate in the market. We believe those forces are unlikely to reverse in the near term and may continue removing capacity from the system.
As a result, our base case is that capacity replacement will occur more slowly than in prior trucking cycles. Before COVID, markets typically self-corrected as higher rates attracted drivers, equipment, and new entrants. Today, new capacity must also satisfy a broader set of compliance, safety, insurance, and documentation standards before it becomes commercially deployable. That creates a structural bottleneck that could extend well beyond the traditional freight cycle.
The most important forward-looking risk is what happens if demand accelerates into this environment. Several macro indicators have begun to improve, and any meaningful recovery in housing, manufacturing, durable goods, or consumer activity would likely arrive against a capacity base that is already tightening. In that scenario, freight markets could experience sharper rate inflation than many participants currently expect because demand would be moving faster than replacement capacity can enter the market.
9
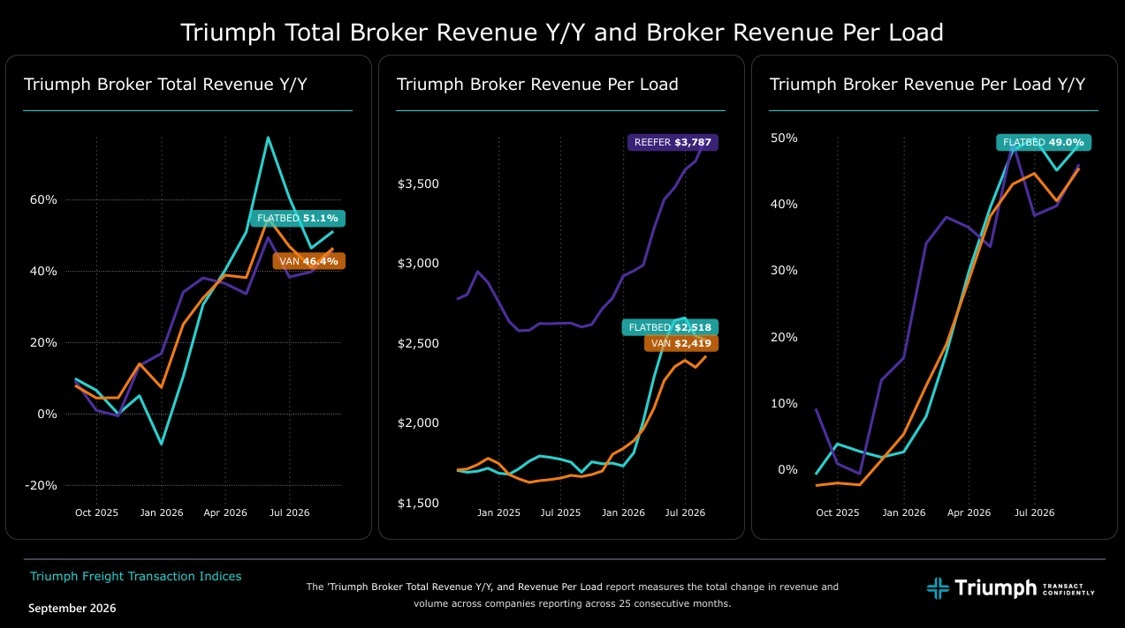
We are also watching the evolution of broker economics closely. Current transaction data shows that higher rates have not translated into proportionately higher margin percentages on an average load basis. However, total broker gross margins and market volumes have continued to improve, suggesting that brokers are increasingly being relied upon to solve capacity challenges as route guides become less reliable, or as shippers consolidate brokers. If capacity constraints persist, network scale, carrier relationships, and access to verified capacity should become increasingly valuable competitive advantages.
Taken together, the data points toward a market that remains early in a supply-driven tightening cycle. Our view is that the industry’s defining question over the next 12 to 24 months will not be whether freight demand recovers; it will be whether defensible capacity can recover alongside it. Based on what we see in transaction-level activity, the answer is likely to be “not quickly,” creating the potential for a longer-lasting and more structurally supportive freight environment than market participants have experienced in prior recoveries.
Banking
1.Analysis of Financial and Operational Performance for the Quarter
2.Deposit Costs and Mortgage Warehouse Economics
3.Update on Credit Metrics
Analysis of Financial and Operational Performance for the Quarter. Banking segment operating income was $24.1 million, compared with $24.2 million in the prior quarter. Net interest income and fee income grew while operating expenses declined, but these improvements were offset by higher credit expense. The bank continues to serve two essential purposes: it generates durable earnings through disciplined banking activities, and it provides the funding and balance-sheet infrastructure that supports the transportation value chain. We remain focused on maintaining a healthy, low-cost funding base, allocating capital toward strategically aligned assets, and reducing credit exposures that might create volatility.
Deposit Costs and Mortgage Warehouse Economics. Investors will remember from prior quarters that the cost of deposits, interest bearing deposits, and total funds that we report include the impact of rebates on our mortgage warehouse servicing deposits. We acknowledge that this produces results that can be confusing without more context.
Our mortgage warehouse deposit balances, which come from the servicing operations of our mortgage warehouse clients, averaged $2.6 billion during the quarter. These deposits are non-interest bearing deposits to the owner of the funds, so that is how we classify them on our balance sheet.
We compensate our clients (the mortgage companies) for these deposits via an interest rebate on their loans – similarly to the way an earnings credit rate might be applied to treasury management fees for a traditional commercial deposit account. Historically, we recognized the full cost of these rebates as an offset to interest income. Those balances have grown materially so far this year, and for some clients the rebates now exceed the interest they pay us on their loans. When that happens, we record the rebate as an offset to interest income until that client’s interest paid to us is reduced to zero, and we record the excess as interest expense. Because the related deposit balances are technically not interest bearing, the interest expense we record inflates the calculated average cost of our interest bearing deposits. We show you the impact on deposit costs in the Mortgage Warehouse Excess Rebates schedule included with tables following this letter.
We sell a portion of these deposits overnight to the Federal Reserve, and they enable us to reduce our use of wholesale funding. The total effective cost of these deposits to us is below the rate the Federal Reserve pays on our cash balances, resulting in very low-risk incremental net interest income.
While we are happy with the growth we have experienced this year in our mortgage warehouse deposit business, our traditional community bank deposit franchise continues to provide the foundation of our funding base: roughly $3 billion of deposits with an average cost below 1.15%. Our community bank team deserves a tremendous amount of credit for serving our customers so well that we are able to maintain profitable, value-adding relationships through any rate cycle.
Update on Credit Metrics. After several quarters of improving credit metrics and low (or negative) credit expense, our credit metrics worsened, and we incurred $5.2 million of CLE in the quarter, driven primarily by commercial real estate.
•Total non-performing loans to total loans: increased by 0.99% to 2.64%.
•Total classified assets: increased by ~$3 million to $172 million.
•Past due to total loans: increased by 0.89% to 3.08%.
10
The deterioration in credit metrics was concentrated in three CRE relationships rather than broad-based portfolio migration. The largest increase in non-performing loans came from a $38.4 million relationship comprised of 4 loans where unauthorized liens were placed behind Triumph. The relationship matured and was placed on non-accrual as we pursue resolution. Despite the maturity default, loan payments continue and we have not recognized a credit loss, reflecting our current view of the underlying collateral and expected repayment.
Separately, two property-specific situations contributed to credit expense. In one case, an extraordinary event caused structural damage that led to a disruption in operations. The other involves a property generating positive operating income, but for which stabilized operations have been unable to service debt as originally structured. This resulted in a tax delinquency and forbearance agreement. We believe that the borrower has the means and intent to resolve the tax delinquency and is making payments in accordance with the forbearance agreement.
Our 2027 earnings framework assumes credit costs continue to trend toward a normal level, but credit will never be perfectly linear. We will continue to narrow the fairway of community bank credit, resolve non-core exposures, and maintain the capital and liquidity necessary to absorb unforeseen outcomes should any arise. As stated last quarter, the metrics also reflect credit exposure work tied to some of the business lines we are exiting, as well as normal-course credit noise. We continue to monitor the bankruptcy proceedings related to our Tricolor ABL exposure, and we continue to believe that our loan position is adequately secured by inventory and other assets that serve as our collateral.
Notable Items, Expense Forecast, and Closing Thoughts
Noninterest expense was $102.0 million for the quarter, including $1.1 million of items we do not view as recurring. We also recorded a net $0.4 million of gains associated with asset disposals that we likewise view as nonrecurring. Taken together, these items reduced pretax income by $0.7 million and EPS by $0.02.
As stated in the CEO Summary, we booked $1.1 million of additional expenses that we consider core, but that we do not expect to recur in future periods. We expect 4Q core expense of approximately $100 million.
The path to greater operational efficiency in 2027 is before us, and it is more nuanced than indiscriminate cost reduction. We expect compensation inflation and continued investment in the capabilities that create revenue and protect the enterprise. The hard work is funding those investments through continuous improvement. Automation in Factoring, monetization in Payments, disciplined product development, vendor management, process redesign and the simplification of non-core activities should drive productivity across the enterprise and allow revenue to grow materially faster than expense.
Over the last five years, I have written more than once that “the plan is to stick to the plan.” The headwinds were significant, and the pace was often slower than we would have liked, but we persevered through it. In the process, we built a value chain with network effects and a platform that I believe is better positioned to distribute financial products to the U.S. trucking industry than anyone else in the world. That, of course, is my highly biased opinion. Opinions aside, we are now accountable for converting those investments into revenue growth, margin expansion and earnings. The freight market has become more favorable, but the more important change is inside Triumph: our customer relationships are broader, our data is better, our distribution is stronger, our operating model is more efficient, and our businesses increasingly reinforce one another.
Thank you for your interest in Triumph, and we are thankful for the trust our shareholders have placed in us.
With warm regards,
Aaron P. Graft
Founder, Vice Chairman and CEO
[1] We define Network engagement as the amount of freight touched through our payments, audit, full AP automation and rate intelligence products. It is an indicator of our broker volume density in the market and a key value driver of the Network. Due to the continued increase in market rates, as alluded to last quarter, we are recalibrating the denominator for our market penetration assessment. We are updating the addressable market for 3Q from $135 billion to $145 billion. This reference to brokered freight is specific to domestic truckload (TL) freight only. Thus, this calculation would exclude less than truckload (LTL), parcel, etc. It would also exclude shipper volumes. Admittedly, this is a difficult percentage to calculate with precision, and it will move from year to year. That being said, we can evaluate the number of payments received in our factoring segment as a proxy for the percentage of TL freight Triumph Payments is touching and also use industry data points to make informed assumptions. In the end, this metric is not intended to be a precise measurement in the same way as we would measure earnings. It is a directional and blunt measurement of the reach of the Network.
11
Conference Call Information
Aaron P. Graft, Vice Chairman & CEO, and Brad Voss, CFO, will review the financial results in a conference call with investors and analysts beginning at 9:30 a.m. central time on Thursday, October 22, 2026.
The live video conference may be accessed directly through this link, https://triumph-financial-q3-2026-earnings.open-exchange.net/ or via the Company's IR website at ir.triumph.io through the Financial Results link. An archive of this video conference will subsequently be available at the same location, referenced above, on the Company’s website.
About Triumph Financial
Triumph (NYSE: TFIN) is a transportation-focused financial and technology company that delivers payments, factoring, banking, and intelligence solutions designed to simplify and modernize freight transactions for brokers, carriers, shippers and factors. The company develops technology and financial products that improve operational efficiency, increase transparency and security in transactions, and expand access to working capital across the transportation industry. Headquartered in Dallas, Texas, Triumph’s portfolio includes Triumph, LoadPay and TBK Bank. Learn more at ir.triumph.io.
Forward-Looking Statements
This letter to shareholders contains forward-looking statements. Any statements about our expectations, beliefs, plans, predictions, forecasts, objectives, assumptions or future events or performance are not historical facts and may be forward-looking. You can identify forward-looking statements by the use of forward-looking terminology such as “believes,” “expects,” “could,” “may,” “will,” “should,” “seeks,” “likely,” “intends,” “plans,” “pro forma,” “projects,” “estimates” or “anticipates” or the negative of these words and phrases or similar words or phrases that are predictions of or indicate future events or trends and that do not relate solely to historical matters. You can also identify forward-looking statements by discussions of strategy, plans or intentions. Forward-looking statements involve numerous risks and uncertainties, and you should not rely on them as predictions of future events. Forward-looking statements depend on assumptions, data or methods that may be incorrect or imprecise and we may not be able to realize them. We do not guarantee that the transactions and events described will happen as described (or that they will happen at all). The following factors, among others, could cause actual results and future events to differ materially from those set forth or contemplated in the forward-looking statements: business and economic conditions generally and in the bank and non-bank financial services industries, nationally and within our local market areas; our ability to mitigate our risk exposures; our ability to maintain our historical earnings trends; changes in management personnel; interest rate risk; concentration of our products and services in the transportation industry; credit risk associated with our loan portfolio; lack of seasoning in our loan portfolio; deteriorating asset quality and higher loan charge-offs; time and effort necessary to resolve non-performing assets; inaccuracy of the assumptions and estimates we make in establishing reserves for probable loan losses and other estimates; risks related to the integration of acquired businesses, including our acquisition of Greenscreens, and any future acquisitions; our ability to successfully identify and address the risks associated with our possible future acquisitions, and the risks that our prior and possible future acquisitions make it more difficult for investors to evaluate our business, financial condition and results of operations, and impairs our ability to accurately forecast our future performance; lack of liquidity; fluctuations in the fair value and liquidity of the securities we hold for sale; impairment of investment securities, goodwill, other intangible assets or deferred tax assets; our risk management strategies; environmental liability associated with our lending activities; increased competition in the bank and non-bank financial services industries, nationally, regionally or locally, which may adversely affect pricing and terms; the accuracy of our financial statements and related disclosures; material weaknesses in our internal control over financial reporting; system failures or failures to prevent breaches of our network security; the institution and outcome of litigation and other legal proceedings against us or to which we become subject; changes in carry-forwards of net operating losses; changes in federal tax law or policy; the impact of recent and future legislative and regulatory changes, including changes in banking, securities and tax laws and regulations, such as the Dodd-Frank Act and their application by our regulators as well as privacy, cybersecurity, and artificial intelligence regulation and oversight; governmental monetary and fiscal policies; changes in the scope and cost of FDIC, insurance and other coverages; failure to receive regulatory approval for future acquisitions and increases in our capital requirements.
12
While forward-looking statements reflect our good-faith beliefs, they are not guarantees of future performance. All forward-looking statements are necessarily only estimates of future results. Accordingly, actual results may differ materially from those expressed in or contemplated by the particular forward-looking statement, and, therefore, you are cautioned not to place undue reliance on such statements. Further, any forward-looking statement speaks only as of the date on which it is made, and we undertake no obligation to update any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events or circumstances, except as required by applicable law. For a discussion of such risks and uncertainties, which could cause actual results to differ from those contained in the forward-looking statements, see "Risk Factors" and the forward-looking statement disclosure contained in Triumph Financial’s Annual Report on Form 10-K, filed with the Securities and Exchange Commission on February 11, 2026.
Non-GAAP Financial Measures
This letter to shareholders includes certain non‐GAAP financial measures intended to supplement, not substitute for, comparable GAAP measures. Reconciliations of non‐GAAP financial measures to GAAP financial measures are provided at the end of this letter to shareholders.
13
The following table sets forth key metrics used by Triumph Financial to monitor our operations. Footnotes in this table can be found in our definitions of non-GAAP financial measures at the end of this document.
| As of and for the Three Months Ended | As of and for the Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | September 30, 2026 | September 30, 2025 | ||||||||||||||||||||||||||||||||||
| Financial Highlights: | |||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,680,282 | $ | 7,403,685 | $ | 6,876,715 | $ | 6,380,588 | $ | 6,357,149 | $ | 7,680,282 | $ | 6,357,149 | |||||||||||||||||||||||||||
| Loans held for investment | $ | 5,684,505 | $ | 5,477,091 | $ | 5,189,139 | $ | 4,991,307 | $ | 4,986,922 | $ | 5,684,505 | $ | 4,986,922 | |||||||||||||||||||||||||||
| Deposits | $ | 6,467,973 | $ | 6,217,389 | $ | 5,699,939 | $ | 4,950,216 | $ | 4,955,246 | $ | 6,467,973 | $ | 4,955,246 | |||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 12,628 | $ | 10,568 | $ | 5,554 | $ | 18,412 | $ | 907 | $ | 28,750 | $ | 3,741 | |||||||||||||||||||||||||||
| Performance Ratios - Annualized: | |||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 0.69 | % | 0.63 | % | 0.39 | % | 1.18 | % | 0.11 | % | 0.58 | % | 0.13 | % | |||||||||||||||||||||||||||
| Return on average total equity | 5.39 | % | 4.71 | % | 2.71 | % | 8.14 | % | 0.73 | % | 4.29 | % | 0.90 | % | |||||||||||||||||||||||||||
| Return on average common equity | 5.31 | % | 4.59 | % | 2.48 | % | 8.19 | % | 0.41 | % | 4.16 | % | 0.58 | % | |||||||||||||||||||||||||||
Return on average tangible common equity (1) | 9.18 | % | 8.09 | % | 4.46 | % | 15.00 | % | 0.76 | % | 7.32 | % | 0.94 | % | |||||||||||||||||||||||||||
| Yield on loans | 8.43 | % | 8.56 | % | 7.72 | % | 8.14 | % | 8.17 | % | 8.25 | % | 8.31 | % | |||||||||||||||||||||||||||
| Cost of interest bearing deposits | 4.42 | % | 3.84 | % | 2.07 | % | 2.28 | % | 2.36 | % | 3.38 | % | 2.24 | % | |||||||||||||||||||||||||||
| Cost of total deposits | 1.57 | % | 1.58 | % | 1.07 | % | 1.29 | % | 1.35 | % | 1.43 | % | 1.28 | % | |||||||||||||||||||||||||||
| Cost of total funds | 1.64 | % | 1.66 | % | 1.22 | % | 1.48 | % | 1.55 | % | 1.52 | % | 1.51 | % | |||||||||||||||||||||||||||
| Net interest margin | 5.93 | % | 6.15 | % | 6.06 | % | 6.36 | % | 6.29 | % | 6.04 | % | 6.40 | % | |||||||||||||||||||||||||||
Net noninterest expense to average assets(1) | 4.09 | % | 4.43 | % | 4.85 | % | 4.16 | % | 5.08 | % | 4.43 | % | 5.27 | % | |||||||||||||||||||||||||||
Asset Quality:(2) | |||||||||||||||||||||||||||||||||||||||||
| Past due to total loans | 3.08 | % | 2.19 | % | 2.35 | % | 2.72 | % | 1.91 | % | 3.08 | % | 1.91 | % | |||||||||||||||||||||||||||
| Non-performing loans to total loans | 2.64 | % | 1.65 | % | 1.77 | % | 1.15 | % | 1.36 | % | 2.64 | % | 1.36 | % | |||||||||||||||||||||||||||
| Non-performing assets to total assets | 2.01 | % | 1.29 | % | 1.53 | % | 1.10 | % | 1.10 | % | 2.01 | % | 1.10 | % | |||||||||||||||||||||||||||
| ACL to non-performing loans | 25.67 | % | 38.43 | % | 37.15 | % | 63.44 | % | 49.53 | % | 25.67 | % | 49.53 | % | |||||||||||||||||||||||||||
| ACL to total loans | 0.68 | % | 0.64 | % | 0.66 | % | 0.73 | % | 0.67 | % | 0.68 | % | 0.67 | % | |||||||||||||||||||||||||||
| Net charge-offs to average loans | 0.02 | % | 0.03 | % | 0.04 | % | (0.10 | %) | 0.19 | % | 0.09 | % | 0.49 | % | |||||||||||||||||||||||||||
| Capital: | |||||||||||||||||||||||||||||||||||||||||
Tier 1 capital to average assets(3) | 8.89 | % | 9.15 | % | 9.90 | % | 9.86 | % | 9.55 | % | 8.89 | % | 9.55 | % | |||||||||||||||||||||||||||
Tier 1 capital to risk-weighted assets(3) | 10.52 | % | 10.47 | % | 10.68 | % | 10.74 | % | 10.20 | % | 10.52 | % | 10.20 | % | |||||||||||||||||||||||||||
Common equity tier 1 capital to risk-weighted assets(3) | 9.09 | % | 9.00 | % | 9.14 | % | 9.16 | % | 8.65 | % | 9.09 | % | 8.65 | % | |||||||||||||||||||||||||||
Total capital to risk-weighted assets(3) | 12.12 | % | 12.28 | % | 12.56 | % | 12.71 | % | 12.09 | % | 12.12 | % | 12.09 | % | |||||||||||||||||||||||||||
| Total equity to total assets | 12.74 | % | 13.01 | % | 13.83 | % | 14.76 | % | 14.46 | % | 12.74 | % | 14.46 | % | |||||||||||||||||||||||||||
Tangible common stockholders' equity to tangible assets(1) | 7.38 | % | 7.42 | % | 7.80 | % | 8.26 | % | 7.87 | % | 7.38 | % | 7.87 | % | |||||||||||||||||||||||||||
| Per Share Amounts: | |||||||||||||||||||||||||||||||||||||||||
| Book value per share | $ | 39.03 | $ | 38.43 | $ | 38.05 | $ | 37.73 | $ | 36.79 | $ | 39.03 | $ | 36.79 | |||||||||||||||||||||||||||
Tangible book value per share (1) | $ | 22.47 | $ | 21.76 | $ | 21.21 | $ | 20.77 | $ | 19.70 | $ | 22.47 | $ | 19.70 | |||||||||||||||||||||||||||
| Basic earnings per common share | $ | 0.53 | $ | 0.44 | $ | 0.23 | $ | 0.77 | $ | 0.04 | $ | 1.21 | $ | 0.16 | |||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 0.52 | $ | 0.44 | $ | 0.23 | $ | 0.77 | $ | 0.04 | $ | 1.19 | $ | 0.16 | |||||||||||||||||||||||||||
| Shares outstanding end of period | 23,921,510 | 23,894,537 | 23,806,253 | 23,765,385 | 23,763,401 | 23,921,510 | 23,763,401 | ||||||||||||||||||||||||||||||||||
14
Unaudited consolidated balance sheet as of:
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | ||||||||||||||||||||||||
| ASSETS | |||||||||||||||||||||||||||||
| Total cash and cash equivalents | $ | 1,032,524 | $ | 896,811 | $ | 581,939 | $ | 248,471 | $ | 147,222 | |||||||||||||||||||
| Equity securities with readily determinable fair value | 4,369 | 4,540 | 4,559 | 4,588 | 4,569 | ||||||||||||||||||||||||
| Securities - available for sale | 201,676 | 268,118 | 339,562 | 364,277 | 378,088 | ||||||||||||||||||||||||
| Securities - held to maturity, net | 554 | 977 | 1,031 | 1,550 | 1,766 | ||||||||||||||||||||||||
| Loans held for sale | 2,396 | 1,405 | 2,495 | 459 | 9,741 | ||||||||||||||||||||||||
| Loans held for investment | 5,684,505 | 5,477,091 | 5,189,139 | 4,991,307 | 4,986,922 | ||||||||||||||||||||||||
| Allowance for credit losses | (38,595) | (34,783) | (34,157) | (36,511) | (33,549) | ||||||||||||||||||||||||
| Loans, net | 5,645,910 | 5,442,308 | 5,154,982 | 4,954,796 | 4,953,373 | ||||||||||||||||||||||||
| FHLB and other restricted stock | 3,171 | 3,171 | 4,366 | 14,253 | 14,092 | ||||||||||||||||||||||||
| Premises and equipment, net | 86,628 | 85,968 | 89,492 | 91,071 | 141,141 | ||||||||||||||||||||||||
| Capitalized software, net | 50,803 | 49,873 | 48,322 | 46,370 | 44,934 | ||||||||||||||||||||||||
| Goodwill | 355,296 | 355,296 | 355,296 | 355,296 | 353,898 | ||||||||||||||||||||||||
| Intangible assets, net | 40,765 | 42,925 | 45,372 | 47,888 | 52,291 | ||||||||||||||||||||||||
| Bank-owned life insurance | 65,811 | 65,302 | 65,406 | 64,887 | 64,338 | ||||||||||||||||||||||||
| Deferred tax asset, net | — | — | — | 181 | — | ||||||||||||||||||||||||
| Other assets | 190,379 | 186,991 | 183,893 | 186,501 | 191,696 | ||||||||||||||||||||||||
| Total assets | $ | 7,680,282 | $ | 7,403,685 | $ | 6,876,715 | $ | 6,380,588 | $ | 6,357,149 | |||||||||||||||||||
| LIABILITIES | |||||||||||||||||||||||||||||
| Noninterest bearing deposits | $ | 4,268,448 | $ | 3,780,765 | $ | 3,042,210 | $ | 1,901,638 | $ | 2,095,017 | |||||||||||||||||||
| Interest bearing deposits | 2,199,525 | 2,436,624 | 2,657,729 | 3,048,578 | 2,860,229 | ||||||||||||||||||||||||
| Total deposits | 6,467,973 | 6,217,389 | 5,699,939 | 4,950,216 | 4,955,246 | ||||||||||||||||||||||||
| Federal Home Loan Bank advances | — | — | 30,000 | 280,000 | 280,000 | ||||||||||||||||||||||||
| Subordinated notes | 70,000 | 69,979 | 69,929 | 69,879 | 69,829 | ||||||||||||||||||||||||
| Junior subordinated debentures | 43,491 | 43,321 | 43,154 | 42,991 | 42,829 | ||||||||||||||||||||||||
| Deferred tax liabilities, net | 7,381 | 7,187 | 4,454 | — | 687 | ||||||||||||||||||||||||
| Other liabilities | 112,877 | 102,546 | 78,524 | 95,731 | 89,225 | ||||||||||||||||||||||||
| Total liabilities | 6,701,722 | 6,440,422 | 5,926,000 | 5,438,817 | 5,437,816 | ||||||||||||||||||||||||
| EQUITY | |||||||||||||||||||||||||||||
| Preferred Stock | 45,000 | 45,000 | 45,000 | 45,000 | 45,000 | ||||||||||||||||||||||||
| Common stock | 297 | 297 | 296 | 295 | 295 | ||||||||||||||||||||||||
| Additional paid-in-capital | 610,979 | 605,940 | 601,832 | 597,466 | 593,624 | ||||||||||||||||||||||||
| Treasury stock, at cost | (272,840) | (272,840) | (270,711) | (270,619) | (270,619) | ||||||||||||||||||||||||
| Retained earnings | 600,118 | 587,490 | 576,922 | 571,368 | 552,956 | ||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | (4,994) | (2,624) | (2,624) | (1,739) | (1,923) | ||||||||||||||||||||||||
| Total stockholders' equity | 978,560 | 963,263 | 950,715 | 941,771 | 919,333 | ||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,680,282 | $ | 7,403,685 | $ | 6,876,715 | $ | 6,380,588 | $ | 6,357,149 | |||||||||||||||||||
15
Unaudited consolidated statement of income:
| For the Three Months Ended | For the Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | September 30, 2026 | September 30, 2025 | ||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||
| Loans, including fees | $ | 52,626 | $ | 53,592 | $ | 47,656 | $ | 55,233 | $ | 56,400 | $ | 153,874 | $ | 164,812 | |||||||||||||||||||||||||||
| Factored receivables, including fees | 63,549 | 58,958 | 46,021 | 46,165 | 43,841 | 168,528 | 126,752 | ||||||||||||||||||||||||||||||||||
| Securities | 3,027 | 3,904 | 4,540 | 5,083 | 5,489 | 11,471 | 16,518 | ||||||||||||||||||||||||||||||||||
| FHLB and other stock | 167 | 146 | 272 | 969 | 223 | 585 | 718 | ||||||||||||||||||||||||||||||||||
| Cash deposits | 11,201 | 7,937 | 4,266 | 2,606 | 2,987 | 23,404 | 11,611 | ||||||||||||||||||||||||||||||||||
| Total interest income | 130,570 | 124,537 | 102,755 | 110,056 | 108,940 | 357,862 | 320,411 | ||||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||
| Deposits | 25,827 | 24,027 | 14,052 | 16,639 | 17,532 | 63,906 | 47,434 | ||||||||||||||||||||||||||||||||||
| Subordinated notes | 634 | 663 | 662 | 662 | 661 | 1,959 | 2,004 | ||||||||||||||||||||||||||||||||||
| Junior subordinated debentures | 983 | 965 | 954 | 1,007 | 1,049 | 2,902 | 3,078 | ||||||||||||||||||||||||||||||||||
| Other borrowings | — | 56 | 993 | 2,054 | 1,865 | 1,049 | 7,001 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 27,444 | 25,711 | 16,661 | 20,362 | 21,107 | 69,816 | 59,517 | ||||||||||||||||||||||||||||||||||
| Net interest income | 103,126 | 98,826 | 86,094 | 89,694 | 87,833 | 288,046 | 260,894 | ||||||||||||||||||||||||||||||||||
| Credit loss expense (benefit) | 5,220 | 2,736 | (607) | (1,764) | 4,284 | 7,349 | 4,912 | ||||||||||||||||||||||||||||||||||
| Net interest income after credit loss expense (benefit) | 97,906 | 96,090 | 86,701 | 91,458 | 83,549 | 280,697 | 255,982 | ||||||||||||||||||||||||||||||||||
| Noninterest income: | |||||||||||||||||||||||||||||||||||||||||
| Service charges on deposits | 1,870 | 1,798 | 1,212 | 1,483 | 1,847 | 4,880 | 5,185 | ||||||||||||||||||||||||||||||||||
| Card income | 2,142 | 2,129 | 1,960 | 1,935 | 1,968 | 6,231 | 5,687 | ||||||||||||||||||||||||||||||||||
| Net gains (losses) on sale of loans | 99 | 100 | 87 | 71 | 119 | 286 | 443 | ||||||||||||||||||||||||||||||||||
| Net gains (losses) on disposal of premises and equipment | 333 | (1,779) | 606 | 14,265 | (3) | (840) | 625 | ||||||||||||||||||||||||||||||||||
| Fee income | 15,701 | 15,527 | 13,735 | 13,478 | 14,305 | 44,963 | 36,174 | ||||||||||||||||||||||||||||||||||
| Insurance commissions | 1,201 | 1,006 | 1,111 | (496) | 1,481 | 3,318 | 4,013 | ||||||||||||||||||||||||||||||||||
| Other | 1,200 | 2,634 | 996 | (346) | 1,731 | 4,830 | 5,895 | ||||||||||||||||||||||||||||||||||
| Total noninterest income | 22,546 | 21,415 | 19,707 | 30,390 | 21,448 | 63,668 | 58,022 | ||||||||||||||||||||||||||||||||||
| Noninterest expense: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 58,866 | 60,087 | 58,168 | 55,086 | 60,192 | 177,121 | 178,792 | ||||||||||||||||||||||||||||||||||
| Occupancy, furniture and equipment | 6,935 | 6,364 | 6,501 | 7,431 | 7,862 | 19,800 | 24,443 | ||||||||||||||||||||||||||||||||||
| FDIC insurance and other regulatory assessments | 1,656 | 1,167 | 1,058 | 1,337 | 1,468 | 3,881 | 3,089 | ||||||||||||||||||||||||||||||||||
| Professional fees | 5,516 | 7,089 | 4,763 | 4,286 | 5,228 | 17,368 | 10,972 | ||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 2,436 | 2,486 | 2,516 | 2,826 | 2,956 | 7,438 | 8,756 | ||||||||||||||||||||||||||||||||||
| Advertising and promotion | 1,681 | 1,405 | 1,212 | 1,689 | 2,209 | 4,298 | 5,511 | ||||||||||||||||||||||||||||||||||
| Communications and technology | 14,140 | 11,950 | 13,119 | 12,911 | 12,295 | 39,209 | 36,854 | ||||||||||||||||||||||||||||||||||
| Software amortization | 3,739 | 3,477 | 3,300 | 3,081 | 2,868 | 10,516 | 7,725 | ||||||||||||||||||||||||||||||||||
| Travel and entertainment | 1,479 | 1,208 | 1,520 | 1,147 | 1,043 | 4,207 | 4,154 | ||||||||||||||||||||||||||||||||||
| Other | 5,515 | 6,401 | 6,104 | 8,340 | 7,593 | 18,020 | 24,431 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 101,963 | 101,634 | 98,261 | 98,134 | 103,714 | 301,858 | 304,727 | ||||||||||||||||||||||||||||||||||
| Net income before income tax | 18,489 | 15,871 | 8,147 | 23,714 | 1,283 | 42,507 | 9,277 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 5,060 | 4,501 | 1,792 | 4,500 | (425) | 11,353 | 3,132 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 13,429 | $ | 11,370 | $ | 6,355 | $ | 19,214 | $ | 1,708 | $ | 31,154 | $ | 6,145 | |||||||||||||||||||||||||||
| Dividends on preferred stock | (801) | (802) | (801) | (802) | (801) | (2,404) | (2,404) | ||||||||||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 12,628 | $ | 10,568 | $ | 5,554 | $ | 18,412 | $ | 907 | $ | 28,750 | $ | 3,741 | |||||||||||||||||||||||||||
16
Earnings per share:
| For the Three Months Ended | For the Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | September 30, 2026 | September 30, 2025 | ||||||||||||||||||||||||||||||||||
| Basic | |||||||||||||||||||||||||||||||||||||||||
| Net income (loss) to common stockholders | $ | 12,628 | $ | 10,568 | $ | 5,554 | $ | 18,412 | $ | 907 | $ | 28,750 | $ | 3,741 | |||||||||||||||||||||||||||
| Weighted average common shares outstanding | 23,911,970 | 23,865,432 | 23,787,051 | 23,764,954 | 23,752,331 | 23,855,275 | 23,569,712 | ||||||||||||||||||||||||||||||||||
| Basic earnings (loss) per common share | $ | 0.53 | $ | 0.44 | $ | 0.23 | $ | 0.77 | $ | 0.04 | $ | 1.21 | $ | 0.16 | |||||||||||||||||||||||||||
| Diluted | |||||||||||||||||||||||||||||||||||||||||
| Net income (loss) to common stockholders - diluted | $ | 12,628 | $ | 10,568 | $ | 5,554 | $ | 18,412 | $ | 907 | $ | 28,750 | $ | 3,741 | |||||||||||||||||||||||||||
| Weighted average common shares outstanding | 23,911,970 | 23,865,432 | 23,787,051 | 23,764,954 | 23,752,331 | 23,855,275 | 23,569,712 | ||||||||||||||||||||||||||||||||||
| Dilutive effects of: | |||||||||||||||||||||||||||||||||||||||||
| Assumed exercises of stock options | 69,162 | 55,497 | 62,027 | 53,795 | 59,389 | 59,530 | 65,104 | ||||||||||||||||||||||||||||||||||
| Restricted stock awards | — | — | — | — | — | — | 20,410 | ||||||||||||||||||||||||||||||||||
| Restricted stock units | 99,947 | 101,847 | 125,664 | 102,264 | 90,675 | 108,886 | 115,441 | ||||||||||||||||||||||||||||||||||
| Performance stock units - market based | 62,673 | 122,961 | 61,150 | 38,245 | 18,812 | 69,875 | 20,699 | ||||||||||||||||||||||||||||||||||
| Employee stock purchase plan | 1,659 | 2,772 | 263 | 2,645 | 3,651 | 1,565 | 4,083 | ||||||||||||||||||||||||||||||||||
| Weighted average shares outstanding - diluted | 24,145,411 | 24,148,509 | 24,036,155 | 23,961,903 | 23,924,858 | 24,095,131 | 23,795,449 | ||||||||||||||||||||||||||||||||||
| Diluted earnings (loss) per common share | $ | 0.52 | $ | 0.44 | $ | 0.23 | $ | 0.77 | $ | 0.04 | $ | 1.19 | $ | 0.16 | |||||||||||||||||||||||||||
Shares that were not considered in computing diluted earnings per common share because they were antidilutive or have not met the thresholds to be considered in the dilutive calculation are as follows:
| For the Three Months Ended | For the Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | September 30, 2026 | September 30, 2025 | |||||||||||||||||||||||||||||||||||
| Stock options | 116,981 | 131,024 | 172,482 | 177,436 | 181,647 | 192,252 | 141,531 | ||||||||||||||||||||||||||||||||||
| Restricted stock awards | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||
| Restricted stock units | — | — | — | — | — | 198 | 3,750 | ||||||||||||||||||||||||||||||||||
| Performance stock units - market based | 65,189 | 88,187 | — | 60,840 | 77,074 | 36,538 | 42,846 | ||||||||||||||||||||||||||||||||||
| Employee stock purchase plan | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||
Loans held for investment summarized as of:
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | ||||||||||||||||||||||||
| Commercial real estate | $ | 662,836 | $ | 667,520 | $ | 724,923 | $ | 730,435 | $ | 769,314 | |||||||||||||||||||
| Construction, land development, land | 196,488 | 192,091 | 206,693 | 224,214 | 204,247 | ||||||||||||||||||||||||
| 1-4 family residential properties | 255,441 | 205,540 | 187,991 | 193,508 | 180,970 | ||||||||||||||||||||||||
| Farmland | 40,534 | 42,909 | 42,666 | 43,433 | 43,208 | ||||||||||||||||||||||||
| Commercial | 1,196,003 | 1,160,128 | 1,112,802 | 1,163,664 | 1,144,872 | ||||||||||||||||||||||||
| Factored receivables | 2,235,188 | 2,135,878 | 1,717,808 | 1,462,900 | 1,424,631 | ||||||||||||||||||||||||
| Consumer | 17,003 | 16,715 | 15,381 | 16,819 | 17,235 | ||||||||||||||||||||||||
| Mortgage warehouse | 1,081,012 | 1,056,310 | 1,180,875 | 1,156,334 | 1,202,445 | ||||||||||||||||||||||||
| Total loans | $ | 5,684,505 | $ | 5,477,091 | $ | 5,189,139 | $ | 4,991,307 | $ | 4,986,922 | |||||||||||||||||||
17
Our banking loan portfolio consists of traditional community bank loans as well as commercial finance product lines focused on businesses that require specialized financial solutions and national lending product lines that further diversify our lending operations.
Banking loans held for investment are further summarized below:
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | ||||||||||||||||||||||||
| Commercial real estate | $ | 662,836 | $ | 667,520 | $ | 724,923 | $ | 730,435 | $ | 769,314 | |||||||||||||||||||
| Construction, land development, land | 196,488 | 192,091 | 206,693 | 224,214 | 204,247 | ||||||||||||||||||||||||
| 1-4 family residential | 255,441 | 205,540 | 187,991 | 193,508 | 180,970 | ||||||||||||||||||||||||
| Farmland | 40,534 | 42,909 | 42,666 | 43,433 | 43,208 | ||||||||||||||||||||||||
| Commercial - General | 340,154 | 322,969 | 303,561 | 313,696 | 285,571 | ||||||||||||||||||||||||
| Commercial - Agriculture | 51,229 | 51,130 | 44,396 | 42,588 | 49,742 | ||||||||||||||||||||||||
| Commercial - Equipment | 669,355 | 621,884 | 583,374 | 587,926 | 564,984 | ||||||||||||||||||||||||
| Commercial - Asset-based lending | 97,933 | 123,053 | 138,982 | 180,012 | 198,809 | ||||||||||||||||||||||||
| Commercial - Liquid Credit | 34,446 | 37,091 | 38,579 | 36,482 | 42,593 | ||||||||||||||||||||||||
| Consumer | 17,003 | 16,715 | 15,381 | 16,819 | 17,235 | ||||||||||||||||||||||||
| Mortgage Warehouse | 1,081,012 | 1,056,310 | 1,180,875 | 1,156,334 | 1,202,445 | ||||||||||||||||||||||||
| Total banking loans held for investment | $ | 3,446,431 | $ | 3,337,212 | $ | 3,467,421 | $ | 3,525,447 | $ | 3,559,118 | |||||||||||||||||||
The following table presents the Company’s operating segments:
| (Dollars in thousands) | Total | Corporate | ||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended September 30, 2026 | Banking | Factoring | Payments | Intelligence | Segments | and Other(1) | Consolidated | |||||||||||||||||||||||||||||||||||||
| Total interest income | $ | 66,884 | $ | 54,051 | $ | 9,601 | $ | — | $ | 130,536 | $ | 34 | $ | 130,570 | ||||||||||||||||||||||||||||||
| Intersegment interest allocations | 9,566 | (11,471) | 1,905 | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 25,822 | 6 | — | — | 25,828 | 1,616 | 27,444 | |||||||||||||||||||||||||||||||||||||
| Net interest income (expense) | 50,628 | 42,574 | 11,506 | — | 104,708 | (1,582) | 103,126 | |||||||||||||||||||||||||||||||||||||
| Credit loss expense (benefit) | 3,260 | 1,469 | 130 | — | 4,859 | 361 | 5,220 | |||||||||||||||||||||||||||||||||||||
| Net interest income after credit loss expense | 47,368 | 41,105 | 11,376 | — | 99,849 | (1,943) | 97,906 | |||||||||||||||||||||||||||||||||||||
| Noninterest income | 6,836 | 1,989 | 11,768 | 2,360 | 22,953 | (407) | 22,546 | |||||||||||||||||||||||||||||||||||||
| Noninterest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 15,123 | 12,068 | 9,249 | 2,756 | 39,196 | 19,670 | 58,866 | |||||||||||||||||||||||||||||||||||||
| Depreciation | 1,480 | 680 | 165 | 16 | 2,341 | 782 | 3,123 | |||||||||||||||||||||||||||||||||||||
| Other occupancy, furniture and equipment | 2,123 | 511 | 194 | 14 | 2,842 | 970 | 3,812 | |||||||||||||||||||||||||||||||||||||
| FDIC insurance and other regulatory assessments | 1,656 | — | — | — | 1,656 | — | 1,656 | |||||||||||||||||||||||||||||||||||||
| Professional fees | 2,483 | 615 | 517 | 100 | 3,715 | 1,801 | 5,516 | |||||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 253 | 59 | 812 | 1,284 | 2,408 | 28 | 2,436 | |||||||||||||||||||||||||||||||||||||
| Advertising and promotion | 372 | 487 | 361 | 119 | 1,339 | 342 | 1,681 | |||||||||||||||||||||||||||||||||||||
| Communications and technology | 3,623 | 2,896 | 3,800 | 423 | 10,742 | 3,398 | 14,140 | |||||||||||||||||||||||||||||||||||||
| Software amortization | — | 1,189 | 2,112 | 87 | 3,388 | 351 | 3,739 | |||||||||||||||||||||||||||||||||||||
| Travel and entertainment | 203 | 117 | 220 | 86 | 626 | 853 | 1,479 | |||||||||||||||||||||||||||||||||||||
| Other | 2,957 | 522 | 891 | 48 | 4,418 | 1,097 | 5,515 | |||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 30,273 | 19,144 | 18,321 | 4,933 | 72,671 | 29,292 | 101,963 | |||||||||||||||||||||||||||||||||||||
Net intersegment noninterest income (expense)(2) | 152 | 517 | (669) | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Operating income (loss) | $ | 24,083 | $ | 24,467 | $ | 4,154 | $ | (2,573) | $ | 50,131 | $ | (31,642) | $ | 18,489 | ||||||||||||||||||||||||||||||
18
| (Dollars in thousands) | Total | Corporate | ||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended June 30, 2026 | Banking | Factoring | Payments | Intelligence | Segments | and Other(1) | Consolidated | |||||||||||||||||||||||||||||||||||||
| Total interest income | $ | 65,381 | $ | 50,166 | $ | 8,957 | $ | — | $ | 124,504 | $ | 33 | $ | 124,537 | ||||||||||||||||||||||||||||||
| Intersegment interest allocations | 8,405 | (10,585) | 2,180 | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 24,076 | 7 | — | — | 24,083 | 1,628 | 25,711 | |||||||||||||||||||||||||||||||||||||
| Net interest income (expense) | 49,710 | 39,574 | 11,137 | — | 100,421 | (1,595) | 98,826 | |||||||||||||||||||||||||||||||||||||
| Credit loss expense (benefit) | (30) | 2,716 | 155 | — | 2,841 | (105) | 2,736 | |||||||||||||||||||||||||||||||||||||
| Net interest income after credit loss expense | 49,740 | 36,858 | 10,982 | — | 97,580 | (1,490) | 96,090 | |||||||||||||||||||||||||||||||||||||
| Noninterest income | 5,331 | 1,917 | 10,893 | 2,389 | 20,530 | 885 | 21,415 | |||||||||||||||||||||||||||||||||||||
| Noninterest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 14,684 | 12,452 | 9,771 | 3,449 | 40,356 | 19,731 | 60,087 | |||||||||||||||||||||||||||||||||||||
| Depreciation | 1,540 | 273 | 156 | 18 | 1,987 | 776 | 2,763 | |||||||||||||||||||||||||||||||||||||
| Other occupancy, furniture and equipment | 2,128 | 463 | 163 | 13 | 2,767 | 834 | 3,601 | |||||||||||||||||||||||||||||||||||||
| FDIC insurance and other regulatory assessments | 1,167 | — | — | — | 1,167 | — | 1,167 | |||||||||||||||||||||||||||||||||||||
| Professional fees | 4,356 | 436 | 300 | 112 | 5,204 | 1,885 | 7,089 | |||||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 269 | 111 | 812 | 1,283 | 2,475 | 11 | 2,486 | |||||||||||||||||||||||||||||||||||||
| Advertising and promotion | 317 | 383 | 333 | 24 | 1,057 | 348 | 1,405 | |||||||||||||||||||||||||||||||||||||
| Communications and technology | 3,405 | 2,459 | 3,106 | 358 | 9,328 | 2,622 | 11,950 | |||||||||||||||||||||||||||||||||||||
| Software amortization | — | 1,117 | 1,932 | 77 | 3,126 | 351 | 3,477 | |||||||||||||||||||||||||||||||||||||
| Travel and entertainment | 210 | 156 | 219 | 115 | 700 | 508 | 1,208 | |||||||||||||||||||||||||||||||||||||
| Other | 2,912 | 567 | 1,583 | 269 | 5,331 | 1,070 | 6,401 | |||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 30,988 | 18,417 | 18,375 | 5,718 | 73,498 | 28,136 | 101,634 | |||||||||||||||||||||||||||||||||||||
Net intersegment noninterest income (expense)(2) | 144 | 518 | (662) | — | — | — | — | |||||||||||||||||||||||||||||||||||||
| Operating income (loss) | $ | 24,227 | $ | 20,876 | $ | 2,838 | $ | (3,329) | $ | 44,612 | $ | (28,741) | $ | 15,871 | ||||||||||||||||||||||||||||||
(1) Includes revenue and expense from the Company’s holding company, which does not meet the definition of an operating segment. Also includes corporate shared service costs such as the majority of salaries and benefits expense for our executive leadership team, as well as other selling, general, and administrative shared services costs including human resources, accounting, finance, risk management and a significant amount of information technology expense.
(2) Intersegment noninterest income (expense) includes:
| (Dollars in thousands) | Banking | Factoring | Payments | |||||||||||||||||
| Three Months Ended September 30, 2026 | ||||||||||||||||||||
| Factoring revenue received from Payments | $ | — | $ | 911 | $ | (911) | ||||||||||||||
| Payments revenue received from Factoring | — | (261) | 261 | |||||||||||||||||
| Banking revenue received from Payments and Factoring | 152 | (133) | (19) | |||||||||||||||||
| Intersegment noninterest income (expense) | $ | 152 | $ | 517 | $ | (669) | ||||||||||||||
| Three Months Ended June 30, 2026 | ||||||||||||||||||||
| Factoring revenue received from Payments | $ | — | $ | 910 | $ | (910) | ||||||||||||||
| Payments revenue received from Factoring | — | (266) | 266 | |||||||||||||||||
| Banking revenue received from Payments and Factoring | 144 | (126) | (18) | |||||||||||||||||
| Intersegment noninterest income (expense) | $ | 144 | $ | 518 | $ | (662) | ||||||||||||||
19
Information pertaining to our Factoring segment, summarized as of and for the quarters ended:
| Factoring | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | |||||||||||||||||||||||||||
| Factored receivable period end balance | $ | 1,832,253,000 | $ | 1,748,491,000 | $ | 1,404,958,000 | $ | 1,220,780,000 | $ | 1,193,849,000 | ||||||||||||||||||||||
| Commercial loans period end balance | $ | 2,886,000 | $ | 4,001,000 | $ | 3,910,000 | $ | 2,960,000 | $ | 3,173,000 | ||||||||||||||||||||||
| Yield on average receivable balance | 12.46 | % | 12.73 | % | 12.44 | % | 12.79 | % | 12.63 | % | ||||||||||||||||||||||
| Current quarter charge-off rate | 0.05 | % | 0.02 | % | 0.11 | % | 0.03 | % | 0.33 | % | ||||||||||||||||||||||
| Factored receivables - transportation concentration | 97 | % | 97 | % | 96 | % | 97 | % | 96 | % | ||||||||||||||||||||||
| Interest income, including fees | $ | 54,051,000 | $ | 50,166,000 | $ | 38,944,000 | $ | 39,336,000 | $ | 37,157,000 | ||||||||||||||||||||||
| Noninterest income | 1,989,000 | 1,917,000 | 1,918,000 | 1,687,000 | 1,585,000 | |||||||||||||||||||||||||||
| Intersegment noninterest income | 911,000 | 910,000 | 911,000 | 911,000 | 911,000 | |||||||||||||||||||||||||||
| Factoring total revenue | 56,951,000 | 52,993,000 | 41,773,000 | 41,934,000 | 39,653,000 | |||||||||||||||||||||||||||
| Average net funds employed | 1,635,226,000 | 1,504,189,000 | 1,197,257,000 | 1,143,597,000 | 1,097,229,000 | |||||||||||||||||||||||||||
Yield on average net funds employed(1) | 13.82 | % | 14.13 | % | 14.15 | % | 14.55 | % | 14.34 | % | ||||||||||||||||||||||
| Operating income (loss) | $ | 24,467,000 | $ | 20,876,000 | $ | 14,505,000 | $ | 13,676,000 | $ | 8,212,000 | ||||||||||||||||||||||
| Factoring total revenue | $ | 56,951,000 | $ | 52,993,000 | $ | 41,773,000 | $ | 41,934,000 | $ | 39,653,000 | ||||||||||||||||||||||
Operating margin(1) | 42.96 | % | 39.39 | % | 34.72 | % | 32.61 | % | 20.71 | % | ||||||||||||||||||||||
| Accounts receivable purchased | $ | 4,503,394,000 | $ | 4,117,210,000 | $ | 3,262,610,000 | $ | 3,119,443,000 | $ | 2,997,895,000 | ||||||||||||||||||||||
| Number of invoices purchased | 2,004,137 | 1,870,938 | 1,683,160 | 1,744,811 | 1,735,860 | |||||||||||||||||||||||||||
| Average invoice size | $ | 2,247 | $ | 2,201 | $ | 1,938 | $ | 1,788 | $ | 1,727 | ||||||||||||||||||||||
| Average invoice size - transportation | $ | 2,210 | $ | 2,160 | $ | 1,897 | $ | 1,751 | $ | 1,690 | ||||||||||||||||||||||
| Average invoice size - non-transportation | $ | 7,584 | $ | 6,278 | $ | 5,609 | $ | 4,470 | $ | 4,381 | ||||||||||||||||||||||
(1)Operating margin is a non-GAAP financial measure used as a supplemental measure to evaluate the performance of our Factoring segment. It provides meaningful supplemental information regarding the segment's operational performance and enhances investors' overall understanding of the Factoring segment's profitability and operational efficiency.
20
Information pertaining to our Payments segment, summarized as of and for the quarters ended:
| Payments | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | |||||||||||||||||||||||||||
| Supply chain financing factored receivables | $ | 317,999,000 | $ | 287,454,000 | $ | 222,168,000 | $ | 174,292,000 | $ | 157,662,000 | ||||||||||||||||||||||
| Quickpay and other factored receivables | 84,936,000 | 99,933,000 | 90,682,000 | 67,828,000 | 73,120,000 | |||||||||||||||||||||||||||
| Total factored receivable period end balance | $ | 402,935,000 | $ | 387,387,000 | $ | 312,850,000 | $ | 242,120,000 | $ | 230,782,000 | ||||||||||||||||||||||
| Total revenue | ||||||||||||||||||||||||||||||||
| Supply chain finance interest income | $ | 6,470,000 | $ | 5,676,000 | $ | 4,192,000 | $ | 4,177,000 | $ | 3,895,000 | ||||||||||||||||||||||
| Quickpay interest income | 3,131,000 | 3,281,000 | 2,974,000 | 2,759,000 | 2,874,000 | |||||||||||||||||||||||||||
| Intersegment interest income allocation | 1,905,000 | 2,180,000 | 2,488,000 | 2,779,000 | 2,943,000 | |||||||||||||||||||||||||||
| Total interest income | 11,506,000 | 11,137,000 | 9,654,000 | 9,715,000 | 9,712,000 | |||||||||||||||||||||||||||
| Broker noninterest income | 10,313,000 | 9,536,000 | 7,820,000 | 7,330,000 | 7,131,000 | |||||||||||||||||||||||||||
| Factor noninterest income | 576,000 | 630,000 | 796,000 | 952,000 | 933,000 | |||||||||||||||||||||||||||
| Other noninterest income | 879,000 | 727,000 | 547,000 | 341,000 | 398,000 | |||||||||||||||||||||||||||
| Intersegment noninterest income | 261,000 | 266,000 | 287,000 | 290,000 | 329,000 | |||||||||||||||||||||||||||
| Total noninterest income | 12,029,000 | 11,159,000 | 9,450,000 | 8,913,000 | 8,791,000 | |||||||||||||||||||||||||||
| $ | 23,535,000 | $ | 22,296,000 | $ | 19,104,000 | $ | 18,628,000 | $ | 18,503,000 | |||||||||||||||||||||||
| Total expense | ||||||||||||||||||||||||||||||||
| Credit loss expense (benefit) | $ | 130,000 | $ | 155,000 | $ | 197,000 | $ | 28,000 | $ | 9,000 | ||||||||||||||||||||||
| Noninterest expense | 18,321,000 | 18,375,000 | 16,104,000 | 17,258,000 | 17,094,000 | |||||||||||||||||||||||||||
| Intersegment noninterest expense | 930,000 | 928,000 | 927,000 | 930,000 | 950,000 | |||||||||||||||||||||||||||
| $ | 19,381,000 | $ | 19,458,000 | $ | 17,228,000 | $ | 18,216,000 | $ | 18,053,000 | |||||||||||||||||||||||
| Pre-tax operating income (loss) | $ | 4,154,000 | $ | 2,838,000 | $ | 1,876,000 | $ | 412,000 | $ | 450,000 | ||||||||||||||||||||||
| Depreciation expense | 165,000 | 156,000 | 176,000 | 182,000 | 203,000 | |||||||||||||||||||||||||||
| Software amortization expense | 2,112,000 | 1,932,000 | 1,821,000 | 1,684,000 | 1,550,000 | |||||||||||||||||||||||||||
| Intangible amortization expense | 812,000 | 812,000 | 817,000 | 878,000 | 904,000 | |||||||||||||||||||||||||||
Earnings (losses) before interest, taxes, depreciation, and amortization(1) | $ | 7,243,000 | $ | 5,738,000 | $ | 4,690,000 | $ | 3,156,000 | $ | 3,107,000 | ||||||||||||||||||||||
EBITDA Margin(1) | 30.8 | % | 25.7 | % | 24.5 | % | 16.9 | % | 16.8 | % | ||||||||||||||||||||||
| Number of invoices processed | 9,467,000 | 9,086,400 | 8,220,371 | 9,053,274 | 8,826,848 | |||||||||||||||||||||||||||
| Amount of payments processed | $ | 15,132,596,000 | $ | 13,492,237,000 | $ | 11,014,040,000 | $ | 10,995,478,000 | $ | 10,662,418,000 | ||||||||||||||||||||||
| LoadPay | ||||||||||||||||||||||||||||||||
| Revenue | $ | 791,000 | $ | 652,000 | $ | 437,000 | $ | 345,000 | $ | 218,000 | ||||||||||||||||||||||
| Pre-tax operating income (loss) | $ | (2,144,000) | $ | (2,052,000) | $ | (2,059,000) | $ | (2,584,000) | $ | (2,353,000) | ||||||||||||||||||||||
| Depreciation expense | 26,000 | 23,000 | 21,000 | 21,000 | 20,000 | |||||||||||||||||||||||||||
| Software amortization expense | 486,000 | 416,000 | 374,000 | 324,000 | 289,000 | |||||||||||||||||||||||||||
Earnings (losses) before interest, taxes, depreciation, and amortization(1) | $ | (1,632,000) | $ | (1,613,000) | $ | (1,664,000) | $ | (2,239,000) | $ | (2,044,000) | ||||||||||||||||||||||
| Payments revenue excluding LoadPay | $ | 22,744,000 | $ | 21,644,000 | $ | 18,667,000 | $ | 18,283,000 | $ | 18,285,000 | ||||||||||||||||||||||
Payments EBITDA excluding LoadPay(2) | $ | 8,875,000 | $ | 7,351,000 | $ | 6,354,000 | $ | 5,395,000 | $ | 5,151,000 | ||||||||||||||||||||||
Payments EBITDA Margin excluding LoadPay(2) | 39.0 | % | 34.0 | % | 34.0 | % | 29.5 | % | 28.2 | % | ||||||||||||||||||||||
21
(1)Earnings (losses) before interest, taxes, depreciation, and amortization ("EBITDA") and EBITDA margin are non-GAAP financial measures used as supplemental measures to evaluate the performance of our Payments segment. EBITDA is useful because it provides a clearer view of underlying operating performance by excluding the effects of capital structure, tax regimes, and non-cash depreciation and amortization. EBITDA margin complements EBITDA by illustrating how efficiently revenue is converted into operating profitability.
(2)Payments EBITDA excluding LoadPay and Payments EBITDA Margin excluding LoadPay are non-GAAP financial metrics used as supplemental measures to evaluate the performance of our Payments segment exclusive of the investments associated with LoadPay, which is a relatively new product in its early stages. Such adjusted EBITDA measures provide comparable clarity into the performance of our Payments segment prior to the advent of our LoadPay product.
Information pertaining to our Intelligence segment, summarized as of and for the quarters ended:
| Intelligence | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | |||||||||||||||||||||||||||
| Revenue | $ | 2,360,000 | $ | 2,389,000 | $ | 2,397,000 | $ | 2,347,000 | $ | 2,338,000 | ||||||||||||||||||||||
| Cost of revenue | 368,000 | 365,000 | 333,000 | 283,000 | 266,000 | |||||||||||||||||||||||||||
| Gross profit | 1,992,000 | 2,024,000 | 2,064,000 | 2,064,000 | 2,072,000 | |||||||||||||||||||||||||||
| Selling, general and administrative costs | 4,565,000 | 5,353,000 | 5,067,000 | 4,389,000 | 5,670,000 | |||||||||||||||||||||||||||
| Pre-tax operating income (loss) | $ | (2,573,000) | $ | (3,329,000) | (3,003,000) | (2,325,000) | (3,598,000) | |||||||||||||||||||||||||
Gross Margin(1) | 84 | % | 85 | % | 86 | % | 88 | % | 89 | % | ||||||||||||||||||||||
| Pre-tax operating income (loss) | $ | (2,573,000) | $ | (3,329,000) | $ | (3,003,000) | $ | (2,325,000) | $ | (3,598,000) | ||||||||||||||||||||||
| Depreciation expense | 16,000 | 18,000 | 16,000 | 14,000 | 15,000 | |||||||||||||||||||||||||||
| Software amortization expense | 87,000 | 77,000 | 58,000 | 30,000 | 12,000 | |||||||||||||||||||||||||||
| Intangible amortization expense | 1,284,000 | 1,283,000 | 1,283,000 | 1,291,000 | 1,360,000 | |||||||||||||||||||||||||||
EBITDA(2) | $ | (1,186,000) | $ | (1,951,000) | (1,646,000) | (990,000) | (2,211,000) | |||||||||||||||||||||||||
EBITDA Margin(2) | (50.3) | % | (81.7) | % | (68.7) | % | (42.2) | % | (94.6) | % | ||||||||||||||||||||||
*prior periods not meaningful
(1)Gross margin is a non-GAAP financial measure used as supplemental measure to evaluate the performance of our Intelligence segment. Cost of revenues is comprised primarily of salaries and benefits and communications and technology costs for employees providing services to the Company's customers. This includes the costs of the Company's personnel performing integration, customer support, third-party data center and customer training activities. Cost of revenues also includes the direct costs of third party hosting services. We have elected to exclude amortization expense of capitalized developed software and acquired technology, as well as allocations of fixed asset depreciation expense and occupancy expenses from cost of revenues.
(2)Earnings (losses) before interest, taxes, depreciation, and amortization ("EBITDA") and EBITDA margin are non-GAAP financial measures used as supplemental measures to evaluate the performance of our Intelligence segment. EBITDA is useful because it provides a clearer view of underlying operating performance by excluding the effects of capital structure, tax regimes, and non-cash depreciation and amortization. EBITDA margin complements EBITDA by illustrating how efficiently revenue is converted into operating profitability.
22
Transportation revenue:
| Three Months Ended | Linked Quarter | Year over Year | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Transportation Revenue | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Factoring revenue | $ | 56,951 | $ | 52,993 | $ | 41,773 | $ | 41,934 | $ | 39,653 | $ | 3,958 | 7.5 | % | $ | 17,298 | 43.6 | % | |||||||||||||||||||||||||||||||||||
| Intersegment noninterest income | (911) | (910) | (911) | (911) | (911) | (1) | (0.1) | % | — | — | % | ||||||||||||||||||||||||||||||||||||||||||
| Factoring revenue excluding intersegment noninterest income | $ | 56,040 | $ | 52,083 | $ | 40,862 | $ | 41,023 | $ | 38,742 | $ | 3,957 | 7.6 | % | $ | 17,298 | 44.6 | % | |||||||||||||||||||||||||||||||||||
| Payments revenue | $ | 23,535 | $ | 22,296 | $ | 19,104 | $ | 18,628 | $ | 18,503 | $ | 1,239 | 5.6 | % | $ | 5,032 | 27.2 | % | |||||||||||||||||||||||||||||||||||
| Intersegment noninterest income | (261) | (266) | (287) | (290) | (329) | 5 | 1.9 | % | 68 | 20.7 | % | ||||||||||||||||||||||||||||||||||||||||||
| Payments revenue excluding intersegment noninterest income | $ | 23,274 | $ | 22,030 | $ | 18,817 | $ | 18,338 | $ | 18,174 | $ | 1,244 | 5.6 | % | $ | 5,100 | 28.1 | % | |||||||||||||||||||||||||||||||||||
| Intelligence revenue | $ | 2,360 | $ | 2,389 | $ | 2,397 | $ | 2,347 | $ | 2,338 | $ | (29) | (1.2) | % | $ | 22 | 0.9 | % | |||||||||||||||||||||||||||||||||||
| Transportation revenue | $ | 81,674 | $ | 76,502 | $ | 62,076 | $ | 61,708 | $ | 59,254 | $ | 5,172 | 6.8 | % | $ | 22,420 | 37.8 | % | |||||||||||||||||||||||||||||||||||
Deposits summarized as of:
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | ||||||||||||||||||||||||
| Non-interest bearing demand | $ | 1,628,638 | $ | 1,507,469 | $ | 1,381,901 | $ | 1,233,350 | $ | 1,278,625 | |||||||||||||||||||
| Non-interest bearing demand - mortgage warehouse | 2,639,810 | 2,273,296 | 1,660,309 | 668,288 | 816,392 | ||||||||||||||||||||||||
| Total non-interest bearing demand deposits | 4,268,448 | 3,780,765 | 3,042,210 | 1,901,638 | 2,095,017 | ||||||||||||||||||||||||
| Interest bearing demand | 653,923 | 661,332 | 691,572 | 845,060 | 668,576 | ||||||||||||||||||||||||
| Individual retirement accounts | 34,522 | 35,170 | 35,977 | 37,634 | 39,133 | ||||||||||||||||||||||||
| Money market | 668,344 | 719,455 | 639,651 | 608,036 | 580,748 | ||||||||||||||||||||||||
| Savings | 563,880 | 552,238 | 546,374 | 522,189 | 522,469 | ||||||||||||||||||||||||
| Certificates of deposit | 203,443 | 212,943 | 222,123 | 224,644 | 228,415 | ||||||||||||||||||||||||
| Brokered time deposits | 70,445 | 213,315 | 442,872 | 695,093 | 705,772 | ||||||||||||||||||||||||
| Other brokered deposits | 4,968 | 42,171 | 79,160 | 115,922 | 115,116 | ||||||||||||||||||||||||
| Total deposits | $ | 6,467,973 | $ | 6,217,389 | $ | 5,699,939 | $ | 4,950,216 | $ | 4,955,246 | |||||||||||||||||||
23
Net interest margin summarized for the three months ended:
| September 30, 2026 | June 30, 2026 | ||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Average Balance | Interest | Average Rate(5) | Average Balance | Interest | Average Rate(5) | |||||||||||||||||||||||||||||
| Interest earning assets: | |||||||||||||||||||||||||||||||||||
| Interest earning cash balances | $ | 1,189,410 | $ | 11,201 | 3.74 | % | $ | 862,507 | $ | 7,937 | 3.69 | % | |||||||||||||||||||||||
| Taxable securities | 231,030 | 3,012 | 5.17 | % | 305,173 | 3,889 | 5.11 | % | |||||||||||||||||||||||||||
| Tax-exempt securities | 2,275 | 15 | 2.62 | % | 2,276 | 15 | 2.64 | % | |||||||||||||||||||||||||||
| FHLB and other stock | 3,171 | 167 | 20.89 | % | 4,260 | 146 | 13.75 | % | |||||||||||||||||||||||||||
Loans(1) | 5,470,659 | 116,175 | 8.43 | % | 5,271,228 | 112,550 | 8.56 | % | |||||||||||||||||||||||||||
| Total interest earning assets | $ | 6,896,545 | $ | 130,570 | 7.51 | % | $ | 6,445,444 | $ | 124,537 | 7.75 | % | |||||||||||||||||||||||
| Non-interest earning assets: | |||||||||||||||||||||||||||||||||||
| Other assets | 809,434 | 812,508 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 7,705,979 | $ | 7,257,952 | |||||||||||||||||||||||||||||||
| Interest bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
Interest bearing demand(2) | $ | 669,924 | $ | 16,616 | 9.84 | % | $ | 678,219 | $ | 13,181 | 7.80 | % | |||||||||||||||||||||||
| Individual retirement accounts | 34,623 | 109 | 1.25 | % | 35,623 | 113 | 1.27 | % | |||||||||||||||||||||||||||
| Money market | 685,341 | 4,503 | 2.61 | % | 662,643 | 4,233 | 2.56 | % | |||||||||||||||||||||||||||
| Savings | 563,083 | 1,815 | 1.28 | % | 550,784 | 1,623 | 1.18 | % | |||||||||||||||||||||||||||
| Certificates of deposit | 209,172 | 1,254 | 2.38 | % | 218,365 | 1,334 | 2.45 | % | |||||||||||||||||||||||||||
| Brokered time deposits | 125,150 | 1,219 | 3.86 | % | 306,476 | 3,019 | 3.95 | % | |||||||||||||||||||||||||||
| Other brokered deposits | 33,398 | 311 | 3.69 | % | 56,864 | 524 | 3.70 | % | |||||||||||||||||||||||||||
Total interest bearing deposits(2) | 2,320,691 | 25,827 | 4.42 | % | 2,508,974 | 24,027 | 3.84 | % | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | — | — | — | % | 6,099 | 56 | 3.68 | % | |||||||||||||||||||||||||||
| Subordinated notes | 69,989 | 634 | 3.59 | % | 69,956 | 663 | 3.80 | % | |||||||||||||||||||||||||||
| Junior subordinated debentures | 43,394 | 983 | 8.99 | % | 43,223 | 965 | 8.95 | % | |||||||||||||||||||||||||||
| Total interest bearing liabilities | $ | 2,434,074 | $ | 27,444 | 4.47 | % | $ | 2,628,252 | $ | 25,711 | 3.92 | % | |||||||||||||||||||||||
| Noninterest bearing liabilities and equity: | |||||||||||||||||||||||||||||||||||
| Non-interest bearing demand deposits | 4,189,274 | 3,583,133 | |||||||||||||||||||||||||||||||||
| Other liabilities | 94,270 | 78,159 | |||||||||||||||||||||||||||||||||
| Total equity | 988,361 | 968,408 | |||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,705,979 | $ | 7,257,952 | |||||||||||||||||||||||||||||||
| Net interest income | $ | 103,126 | $ | 98,826 | |||||||||||||||||||||||||||||||
Interest spread(3) | 3.04 | % | 3.83 | % | |||||||||||||||||||||||||||||||
Net interest margin(4) | 5.93 | % | 6.15 | % | |||||||||||||||||||||||||||||||
(1) Loan balance totals include respective nonaccrual assets.
(2) Our mortgage warehouse business is more than self-funded due to the noninterest bearing servicing deposits of its clients. The average balance of such deposits was $2.575 billion for the three months ended September 30, 2026. Given their legal form, these deposits are classified as noninterest bearing deposits on our balance sheet. Despite their classification, many of these deposits are not truly free of cost as we compensate our clients for these balances in the form of an earnings interest rebate rather than deposit interest. As a result, such noninterest bearing deposits first decrease our loan yield before increasing our deposit rates. Because of the recent influx of these deposits, some clients hold significantly higher deposit balances than loan balances. As a result, we are now, in some cases, paying out more in rebates than we earn in interest on a given client’s loans. In those cases, we are recording that excess rebate as deposit interest expense. Whether recorded as interest expense or an offset to interest income, the effect on net interest income and net income is the same: these are profitable funds as they displace more expensive wholesale funding and can be invested risk-free above their cost. During the three months ended September 30, 2026, deposit interest expense recognized on these deposits was $15.7 million.
24
The following table shows the impact of mortgage warehouse excess rebates:
| September 30, 2026 | June 30, 2026 | ||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Average Balance | Interest | Average Rate(5) | Average Balance | Interest | Average Rate(5) | |||||||||||||||||||||||||||||
| Interest bearing demand deposits | $ | 669,924 | $ | 16,616 | 9.84 | % | $ | 678,219 | $ | 13,181 | 7.80 | % | |||||||||||||||||||||||
| Mortgage warehouse excess rebates | $ | 669,924 | 15,710 | 9.30 | % | $ | 678,219 | 12,342 | 7.30 | % | |||||||||||||||||||||||||
| Interest bearing demand deposits excluding mortgage warehouse excess rebates | $ | 669,924 | $ | 906 | 0.54 | % | $ | 678,219 | $ | 839 | 0.50 | % | |||||||||||||||||||||||
| Total interest bearing deposits | $ | 2,320,691 | $ | 25,827 | 4.42 | % | $ | 2,508,974 | $ | 24,027 | 3.84 | % | |||||||||||||||||||||||
| Mortgage warehouse excess rebates | $ | 2,320,691 | 15,710 | 2.69 | % | $ | 2,508,974 | 12,342 | 1.97 | % | |||||||||||||||||||||||||
| Total interest bearing deposits excluding mortgage warehouse excess rebates | $ | 2,320,691 | $ | 10,117 | 1.73 | % | $ | 2,508,974 | $ | 11,685 | 1.87 | % | |||||||||||||||||||||||
(3) Net interest spread is the yield on average interest earning assets less the rate on interest bearing liabilities.
(4) Net interest margin is the ratio of net interest income to average interest earning assets.
(5) Average rates have been annualized.
Additional information pertaining to our loan portfolio, including loans held for investment and loans held for sale, summarized for the quarters ended:
| (Dollars in thousands) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | ||||||||||||||||||||||||
| Average Banking loans | $ | 3,381,276 | $ | 3,362,327 | $ | 3,389,580 | $ | 3,491,230 | $ | 3,484,400 | |||||||||||||||||||
| Average Factoring receivables | 1,721,365 | 1,580,178 | 1,269,715 | 1,219,914 | 1,167,092 | ||||||||||||||||||||||||
| Average Payments receivables | 368,018 | 328,723 | 258,821 | 228,358 | 213,386 | ||||||||||||||||||||||||
| Average total loans | $ | 5,470,659 | $ | 5,271,228 | $ | 4,918,116 | $ | 4,939,502 | $ | 4,864,878 | |||||||||||||||||||
| Banking yield | 6.16 | % | 6.37 | % | 5.69 | % | 6.26 | % | 6.41 | % | |||||||||||||||||||
| Factoring yield | 12.46 | % | 12.73 | % | 12.44 | % | 12.79 | % | 12.63 | % | |||||||||||||||||||
| Payments yield | 10.35 | % | 10.93 | % | 11.23 | % | 12.05 | % | 12.59 | % | |||||||||||||||||||
| Total loan yield | 8.43 | % | 8.56 | % | 7.72 | % | 8.14 | % | 8.17 | % | |||||||||||||||||||
25
Reconciliation of non-GAAP financial measures:
| As of and for the Three Months Ended | As of and for the Nine Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share amounts) | September 30, 2026 | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | September 30, 2026 | September 30, 2025 | |||||||||||||||||||||||||||||||||||||
| Average total stockholders' equity | $ | 988,361 | $ | 968,408 | $ | 952,477 | $ | 937,023 | $ | 925,459 | $ | 969,880 | $ | 912,725 | ||||||||||||||||||||||||||||||
| Average preferred stock liquidation preference | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | |||||||||||||||||||||||||||||||||||||
| Average total common stockholders' equity | 943,361 | 923,408 | 907,477 | 892,023 | 880,459 | 924,880 | 867,725 | |||||||||||||||||||||||||||||||||||||
| Average goodwill and other intangibles | (397,546) | (399,652) | (402,158) | (404,893) | (408,025) | (399,768) | (338,324) | |||||||||||||||||||||||||||||||||||||
| Average tangible common stockholders' equity | $ | 545,815 | $ | 523,756 | $ | 505,319 | $ | 487,130 | $ | 472,434 | $ | 525,112 | $ | 529,401 | ||||||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 12,628 | $ | 10,568 | $ | 5,554 | $ | 18,412 | $ | 907 | $ | 28,750 | $ | 3,741 | ||||||||||||||||||||||||||||||
| Average tangible common equity | 545,815 | 523,756 | 505,319 | 487,130 | 472,434 | 525,112 | 529,401 | |||||||||||||||||||||||||||||||||||||
| Return on average tangible common equity | 9.18 | % | 8.09 | % | 4.46 | % | 15.00 | % | 0.76 | % | 7.32 | % | 0.94 | % | ||||||||||||||||||||||||||||||
| Net non-interest expense to average assets ratio: | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expenses | $ | 101,963 | $ | 101,634 | $ | 98,261 | $ | 98,134 | $ | 103,714 | $ | 301,858 | $ | 304,727 | ||||||||||||||||||||||||||||||
| Noninterest income | $ | 22,546 | $ | 21,415 | $ | 19,707 | $ | 30,390 | $ | 21,448 | $ | 63,668 | $ | 58,022 | ||||||||||||||||||||||||||||||
| Net noninterest expenses | $ | 79,417 | $ | 80,219 | $ | 78,554 | $ | 67,744 | $ | 82,266 | $ | 238,190 | $ | 246,705 | ||||||||||||||||||||||||||||||
| Average total assets | $ | 7,705,979 | $ | 7,257,952 | $ | 6,573,075 | $ | 6,465,547 | $ | 6,425,267 | $ | 7,183,152 | $ | 6,263,681 | ||||||||||||||||||||||||||||||
| Net noninterest expense to average assets ratio | 4.09 | % | 4.43 | % | 4.85 | % | 4.16 | % | 5.08 | % | 4.43 | % | 5.27 | % | ||||||||||||||||||||||||||||||
| Total stockholders' equity | $ | 978,560 | $ | 963,263 | $ | 950,715 | $ | 941,771 | $ | 919,333 | $ | 978,560 | $ | 919,333 | ||||||||||||||||||||||||||||||
| Preferred stock liquidation preference | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | (45,000) | |||||||||||||||||||||||||||||||||||||
| Total common stockholders' equity | 933,560 | 918,263 | 905,715 | 896,771 | 874,333 | 933,560 | 874,333 | |||||||||||||||||||||||||||||||||||||
| Goodwill and other intangibles | (396,061) | (398,221) | (400,668) | (403,184) | (406,189) | (396,061) | (406,189) | |||||||||||||||||||||||||||||||||||||
| Tangible common stockholders' equity | $ | 537,499 | $ | 520,042 | $ | 505,047 | $ | 493,587 | $ | 468,144 | $ | 537,499 | $ | 468,144 | ||||||||||||||||||||||||||||||
| Common shares outstanding | 23,921,510 | 23,894,537 | 23,806,253 | 23,765,385 | 23,763,401 | 23,921,510 | 23,763,401 | |||||||||||||||||||||||||||||||||||||
| Tangible book value per share | $ | 22.47 | $ | 21.76 | $ | 21.21 | $ | 20.77 | $ | 19.70 | $ | 22.47 | $ | 19.70 | ||||||||||||||||||||||||||||||
| Total assets at end of period | $ | 7,680,282 | $ | 7,403,685 | $ | 6,876,715 | $ | 6,380,588 | $ | 6,357,149 | $ | 7,680,282 | $ | 6,357,149 | ||||||||||||||||||||||||||||||
| Goodwill and other intangibles | (396,061) | (398,221) | (400,668) | (403,184) | (406,189) | (396,061) | (406,189) | |||||||||||||||||||||||||||||||||||||
| Tangible assets at period end | $ | 7,284,221 | $ | 7,005,464 | $ | 6,476,047 | $ | 5,977,404 | $ | 5,950,960 | $ | 7,284,221 | $ | 5,950,960 | ||||||||||||||||||||||||||||||
| Tangible common stockholders' equity ratio | 7.38 | % | 7.42 | % | 7.80 | % | 8.26 | % | 7.87 | % | 7.38 | % | 7.87 | % | ||||||||||||||||||||||||||||||
1)Triumph Financial uses certain non-GAAP financial measures to provide meaningful supplemental information regarding Triumph Financial's operational performance and to enhance investors' overall understanding of such financial performance. The non-GAAP measures used by Triumph Financial include the following:
•"Tangible common stockholders' equity" is defined as common stockholders' equity less goodwill and other intangible assets.
•"Total tangible assets" is defined as total assets less goodwill and other intangible assets.
•"Tangible book value per share" is defined as tangible common stockholders' equity divided by total common shares outstanding. This measure is important to investors interested in changes from period-to-period in book value per share exclusive of changes in intangible assets.
•"Tangible common stockholders' equity ratio" is defined as the ratio of tangible common stockholders' equity divided by total tangible assets. We believe that this measure is important to many investors in the marketplace who are interested in relative changes from period-to-period in common equity and total assets, each exclusive of changes in intangible assets.
•"Return on Average Tangible Common Equity" is defined as net income available to common stockholders divided by average tangible common stockholders' equity.
2)Asset quality ratios exclude loans held for sale, except for non-performing assets to total assets.
3)Current quarter ratios are preliminary.
26
Source: Triumph Financial, Inc.
###
Investor Relations:
Luke Wyse
Executive Vice President, Head of Investor Relations
lwyse@tfin.com
214-365-6936
Media Contact:
Amanda Tavackoli
Senior Vice President, Director of Corporate Communication
atavackoli@tfin.com
214-365-6930
27